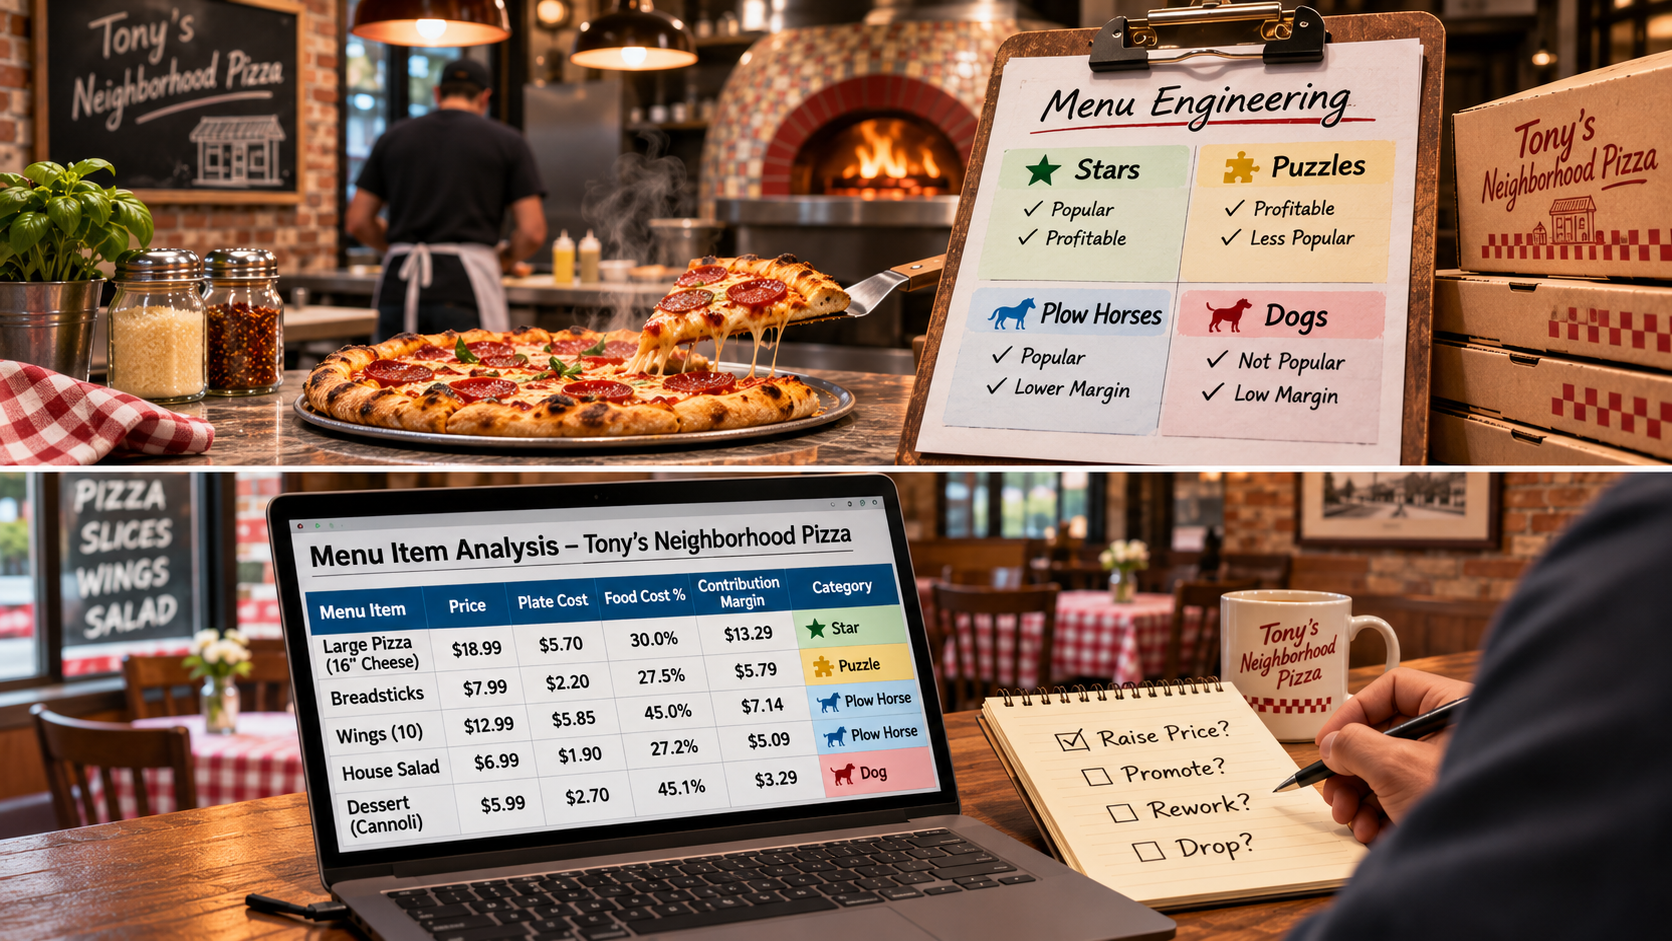
Menu engineering shows which dishes earn your profit. Here's how to cost each item, set prices from a target margin, and sort your menu.
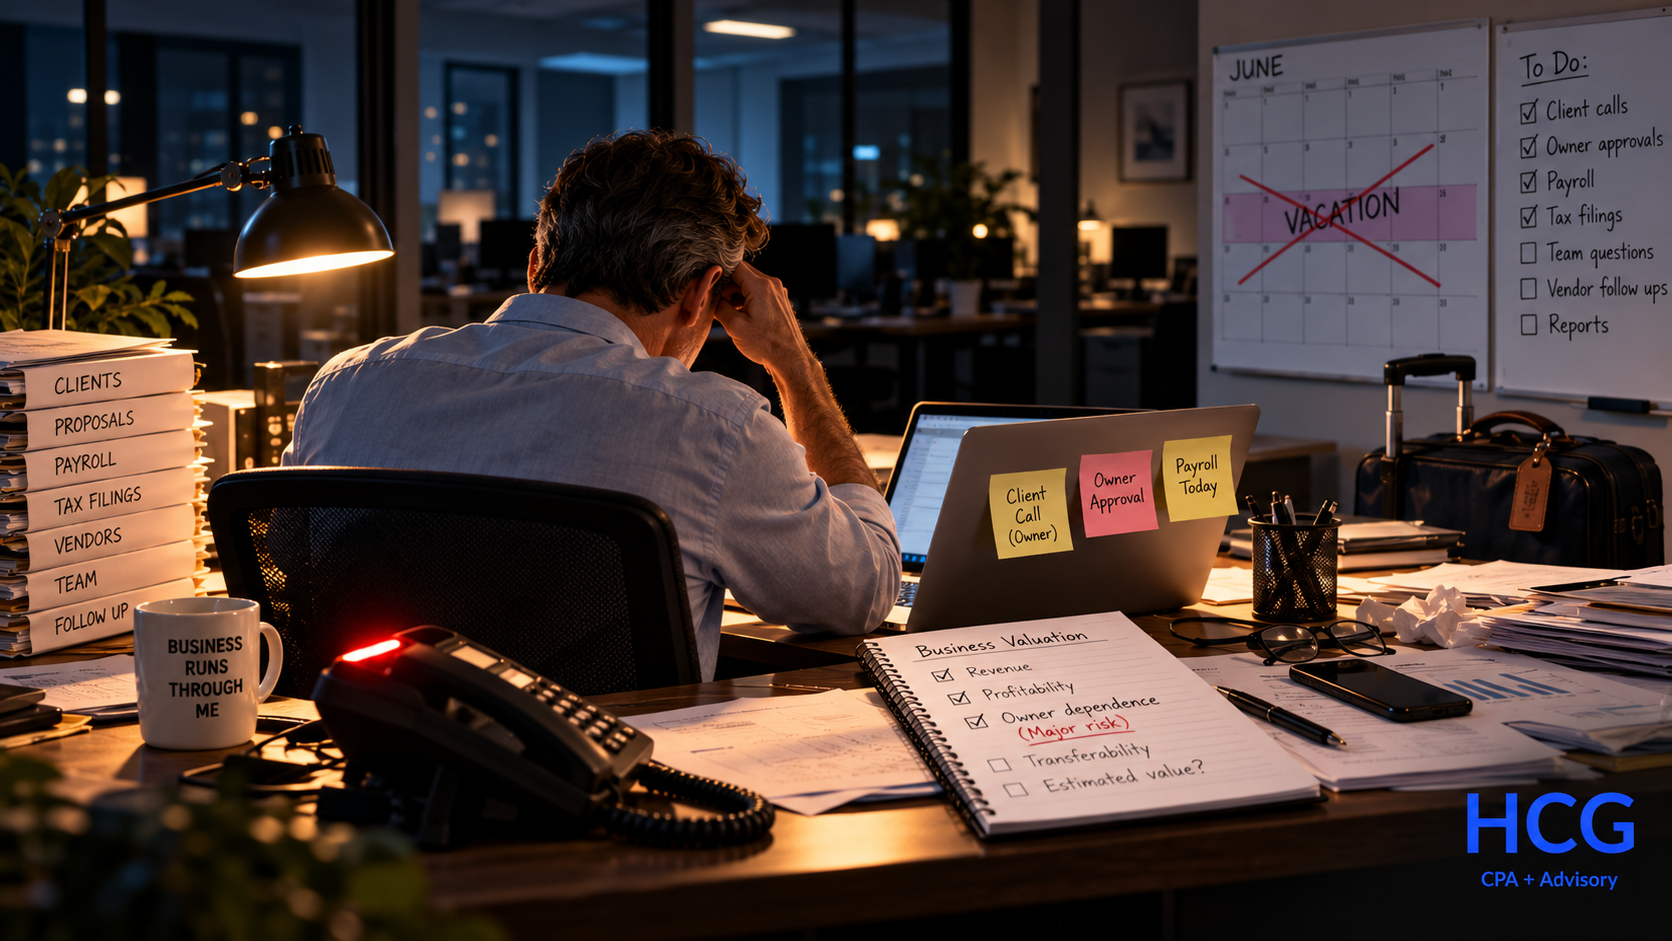
Ask most small business owners what they’re selling, and they’ll point to their client list, their revenue, their reputation. Ask a buyer what they’re actually paying for, and the answer is narrower and less flattering: a system that keeps producing that revenue whether or not a specific person shows up to work. Those are two different things, and the gap between them is where a lot of businesses that look valuable turn out to be much harder to sell than their owner expected. And here is the hidden fact many business owners don't want to acknowledge: If you can't take a vacation, you can't ask for an industry standard valuation, you have to offer a discount right off the bat. There’s a simple way to find out which one you have Here it is: could you take a two-week vacation, leave minimal instructions, and come back to a business that ran normally while you were gone? Not “did a few things slip.” Not “did my manager text me twice.” Normally. Clients served, problems handled, decisions made, nothing waiting on your return except maybe your signature on something that genuinely needed it. If the honest answer is yes, you likely have something close to a sellable business: a product or service that exists independently of you. If the honest answer is no, what you actually have is a personal service business wearing a company name, and that’s a much harder thing to sell at the price you probably have in mind. If you find yourself saying "it could work, but..." then that is really a no that you are refusing to be honest about. Why owners get this wrong about their own business Almost nobody sets out to build a business that depends entirely on them. It happens gradually, and it happens because of things that feel like strengths in the moment. You’re good with people, so you handle every important client relationship yourself. You know the work better than anyone, so it’s faster to just do it than to teach someone else. You care more than anyone else does, so you’re the one who steps in when something goes wrong. Each of those is a reasonable decision on any given day. Add them up over several years, and you’ve built a business where you are the product, not the business itself. The clearest sign this has happened: your best clients would follow you if you left, but wouldn’t necessarily stay if you sold. We have seen this with our own purchases. The prior accountant had wonderful clients and a great relationship. They said all the right things, introduced us and made sure the client was comfortable. The first time there was something new proposed (let's say the prior accountant had missed filing a new state income tax return that was required, for example) the client didn't follow up with us, they called the old accountant. The reason was simple, that relationship is what we bought and it didn't transfer. What this looks like across different businesses A construction company where only the owner can bid a job accurately, because the estimating process lives in his head rather than in a documented system anyone on the team could follow, has an owner-dependency problem even if the backlog looks great on paper. A restaurant where regulars come in specifically to see the owner, and the staff doesn’t have the standing or the training to handle an upset customer the way the owner would, has the same problem dressed up as “great customer service.” You can replace owner with manager or even a great bartender here. The issue is a single person is the center, not the company. An auto dealer where the floor plan lender relationship and the best wholesale contacts exist only in the owner’s personal network, with no one else positioned to maintain them, is sitting on relationships that a buyer can’t actually acquire no matter what the purchase agreement says. In every case, the business looks healthy by the numbers. The problem only shows up when someone tries to transfer it to someone else. Why this matters even more because of what we wrote last time We’ve written before about why a percentage-of-collections structure protects both sides in a service business sale, and about how long-term relationships act as a buffer that resets to zero the moment the familiar person is gone. The vacation test is really asking the same question those two posts are built around: how much of what makes this business work is actually transferable, and how much of it is just you? A business that passes the vacation test has already solved the hardest part of that problem. A buyer isn’t betting on whether your personal relationships survive a transition, because the business was never depending on them alone in the first place. This means higher multiples for your valuation , and you can justify them. A business that fails the test isn’t unsellable. It just means the real work of selling it starts years before a buyer ever shows up, not during negotiations. Failure to realize this ahead of time means lower multiples, terms where the seller carries more risk and overall, a high probability of less money. How to actually pass the test None of this gets fixed quickly, which is exactly why it has to start early. Document the decisions that currently live only in your head. How you price a job, how you handle a difficult customer, how you decide whether to take on a new client. If the answer to “how do we do this” is “ask the owner,” that’s a process waiting to be written down. Give someone else real authority, not just tasks. An employee who can execute what you tell them to do isn’t the same as one who can make the call themselves. The second kind is what lets you actually leave. Introduce clients to your team, not just to you. Every relationship that exists solely between you and a client is a relationship a buyer can’t reliably acquire. Spreading that relationship across two or three people on your team changes that. Actually take the vacation. Not as a test you’re grading from your phone, but a real one. You’ll find out quickly what breaks, and what breaks is your real to-do list. IMPORTANT - Do not cheat on your vacation. Taking your computer, answering calls, responding to emails means you didn't take a vacation, you just worked from a different location. If you have to time your vacation around due dates, you don't have a business that can be sold easily. This is worth doing whether or not you ever sell Here’s the part that’s easy to miss: a business that passes this test isn’t just more valuable to a buyer. It’s less stressful to run , it can grow past what one person can personally manage, and it survives an owner’s illness, a family emergency, or simple burnout. Building toward the vacation test is good management, with a sellable business as a side effect, not the other way around. Where to start If you’re not sure whether your business would pass, that’s worth finding out before you need the answer for a real reason. Schedule a conversation and we’ll talk through what owner-dependency actually looks like in your business and what it would take to change it. Michael Hunsche, CPA, is the founder of HCG CPA + Advisory in Fort Wayne.
The longer a customer knows the person serving them, the more they’ll tolerate a price increase or a mistake. Lose that person, and the same things become reasons to leave.
Selling your accounting practice? Here’s why a percentage-of-collections structure protects both sides, especially for traditional, tax-only CPA firms.
One of Scotland's oldest golf clubs uses single-rider cycles to keep golfers playing. Here's how small Indiana courses can add revenue the same way.
A small Scottish course turned a group of 24 golfers into 24 paying customers. Here's what Indiana courses can learn about 19th hole profits.
Signs You’ve Outgrown Your CPA
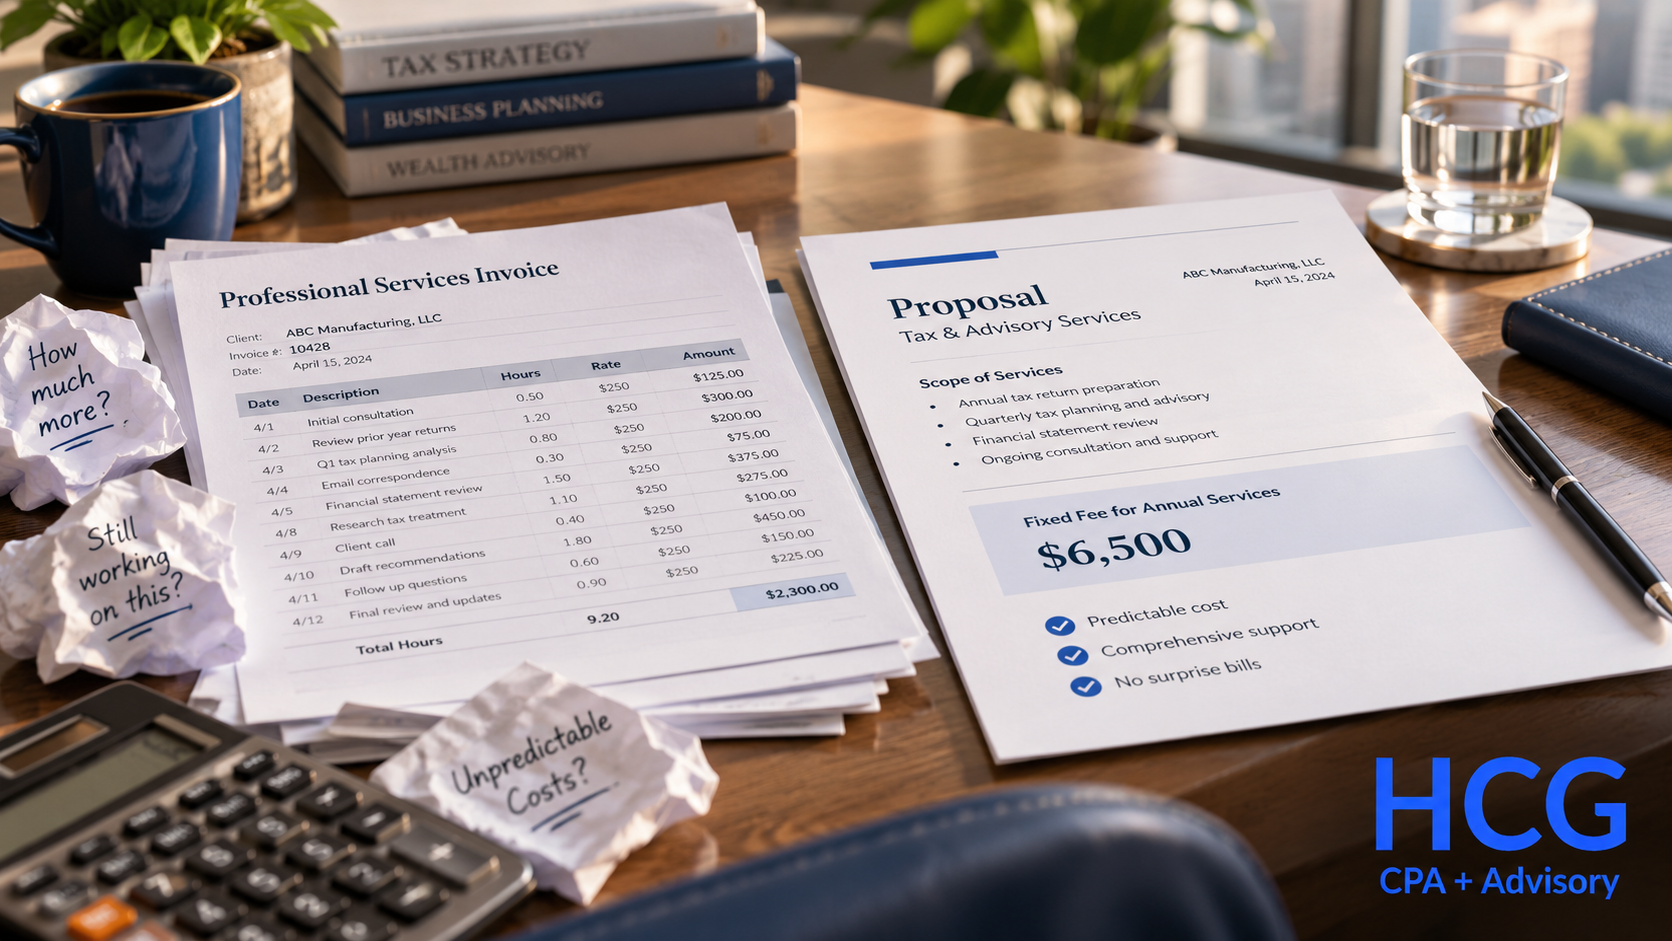
Wondering why your CPA bill is never the same twice? Here’s how hourly billing works against you, and what a predictable fee actually buys you.
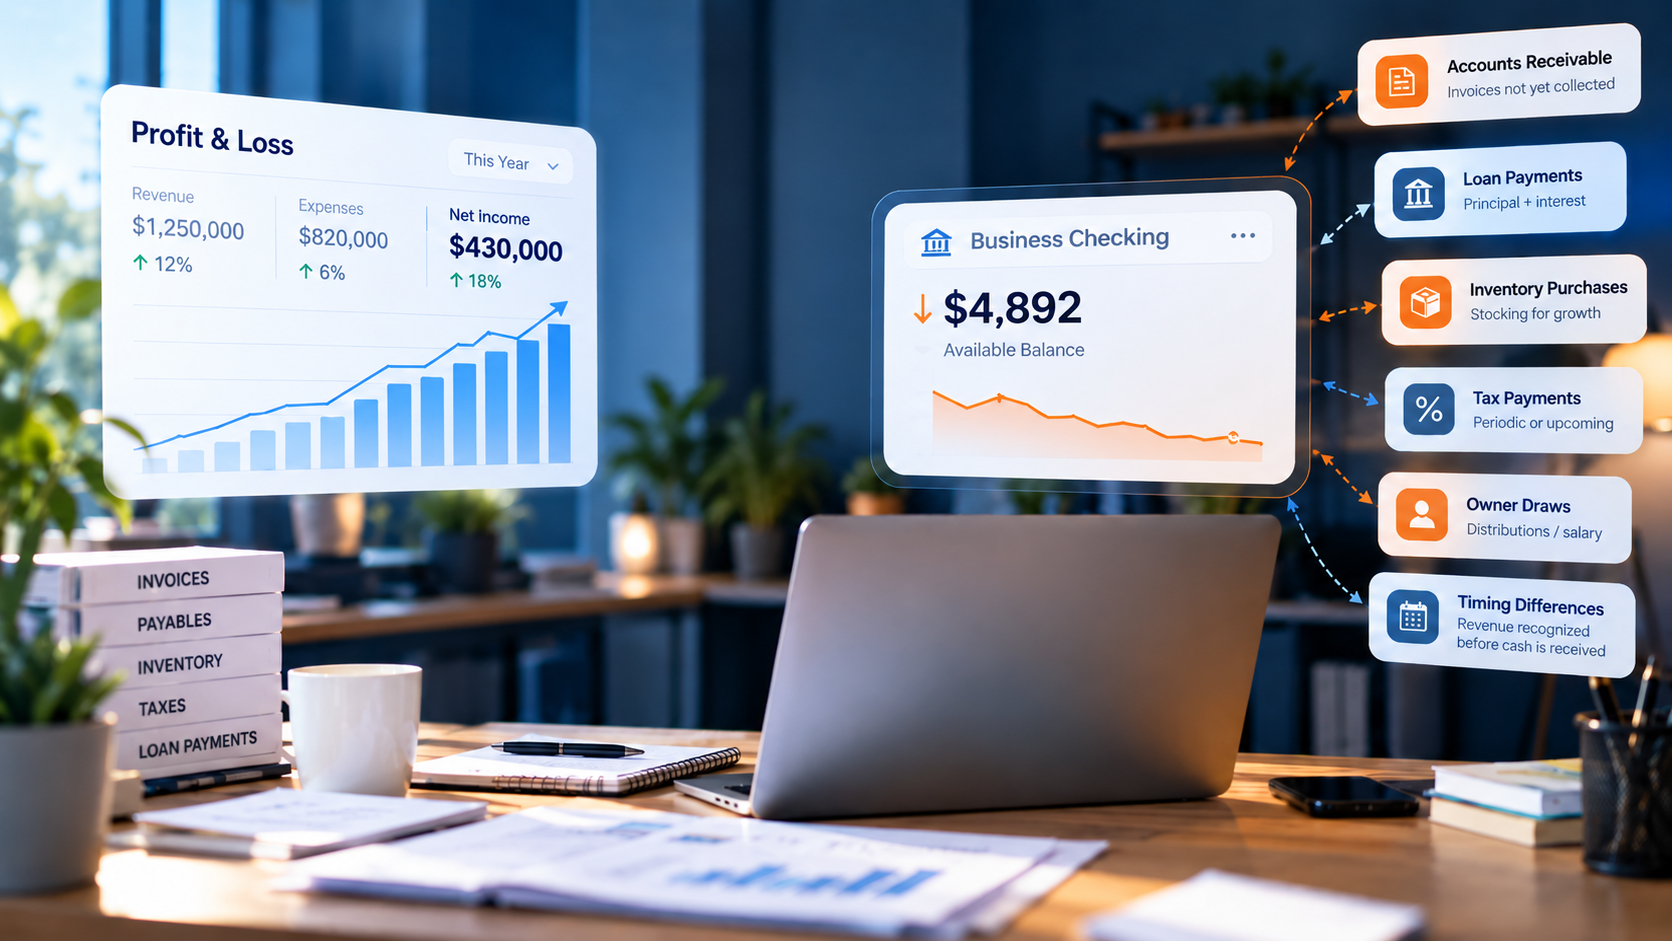
Your financials show a profit, but your bank account doesn't agree. Here's why that happens, and what we look for when it does
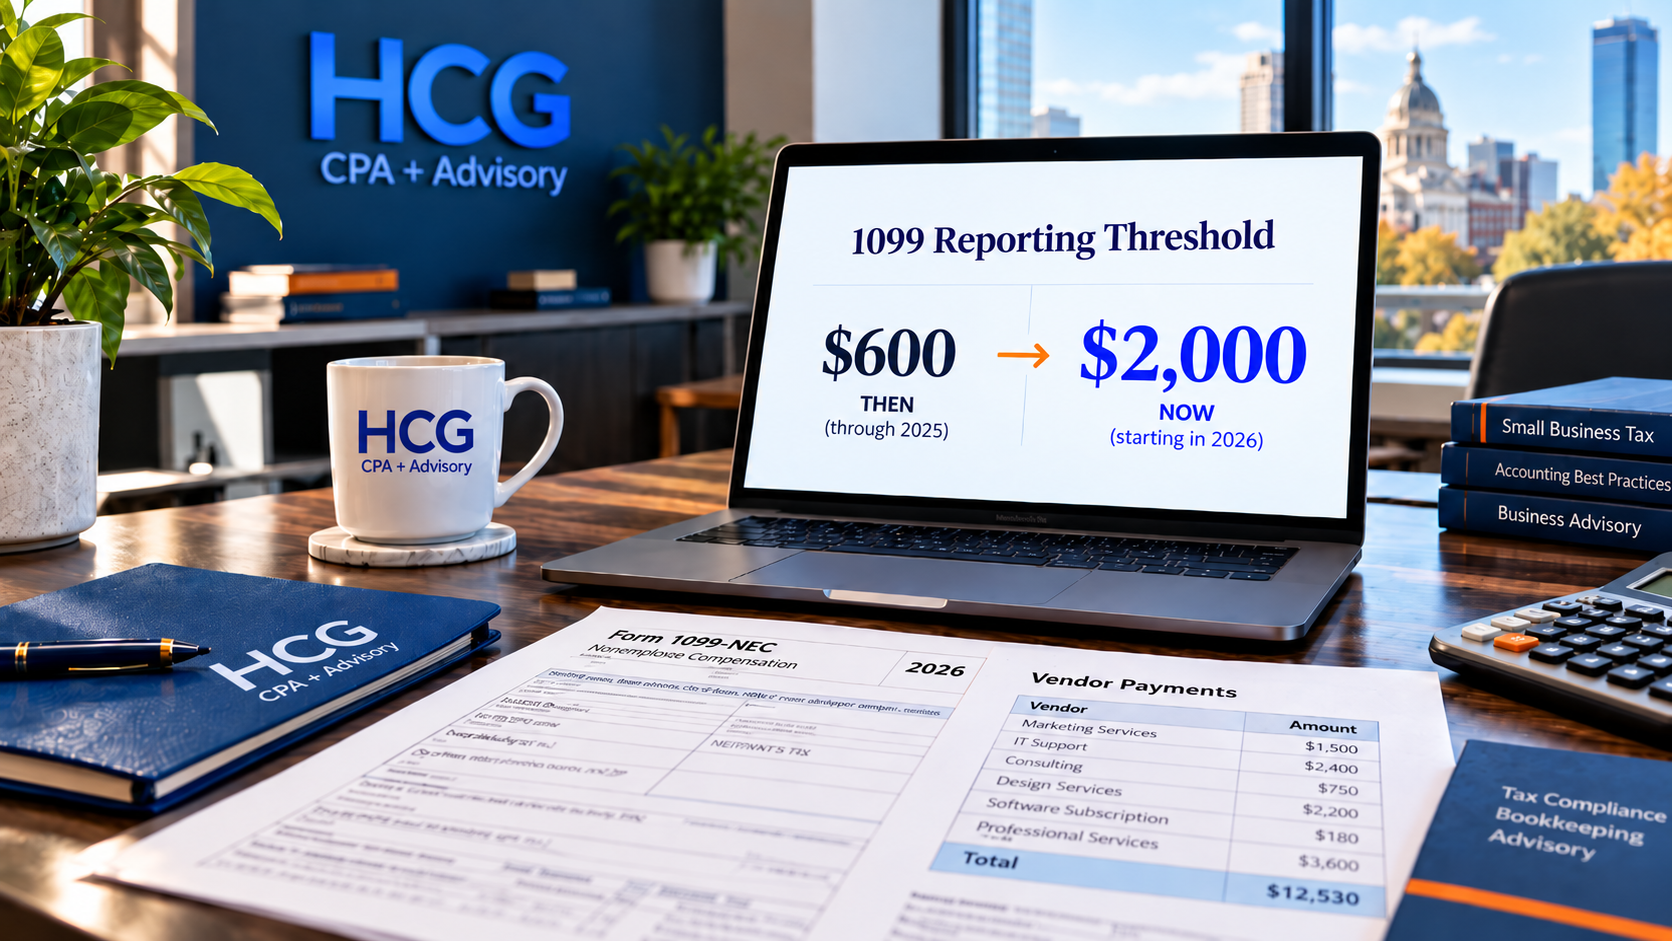
The 1099 reporting threshold jumped from $600 to $2,000 for 2026. Here's why that makes collecting a W-9 before your first payment more important, not less.
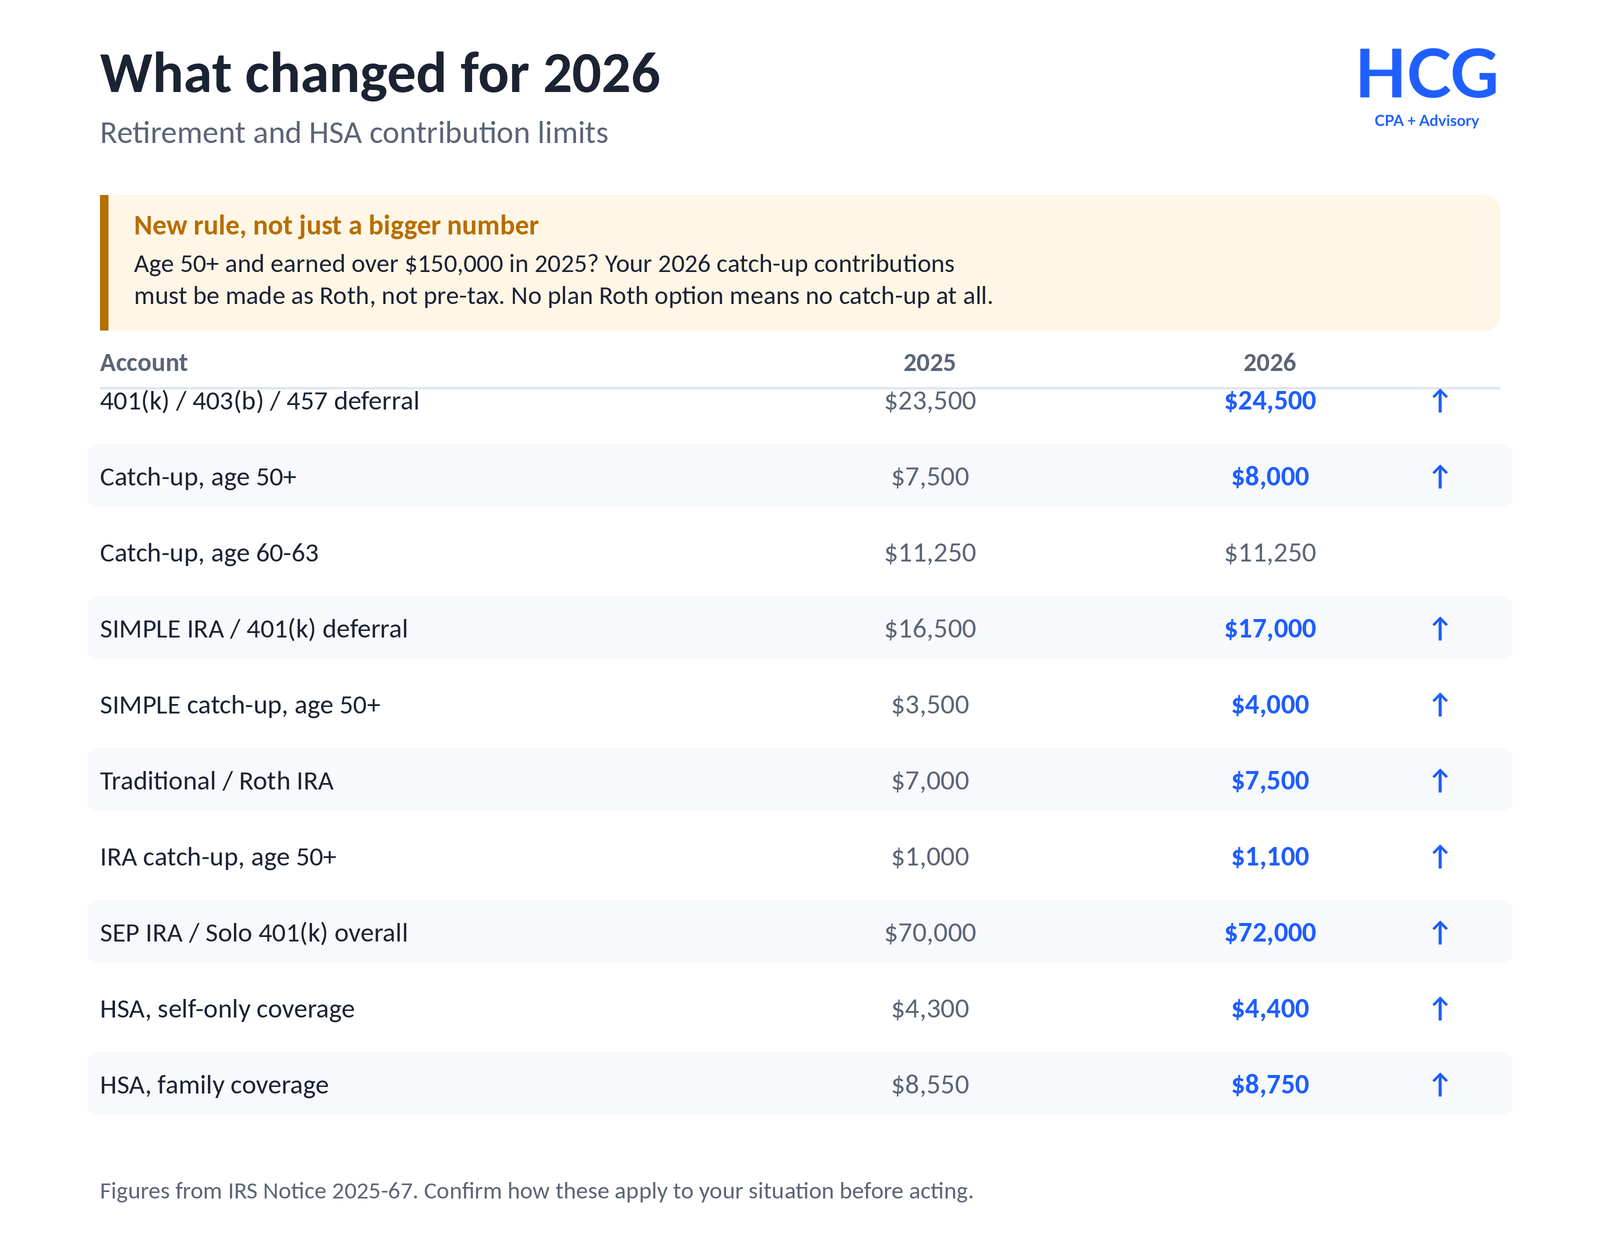
A new Roth rule now applies to retirement catch-up contributions for high earners. Here's why March is too late to plan around it. (147 characters, fits mobile and desktop search results)
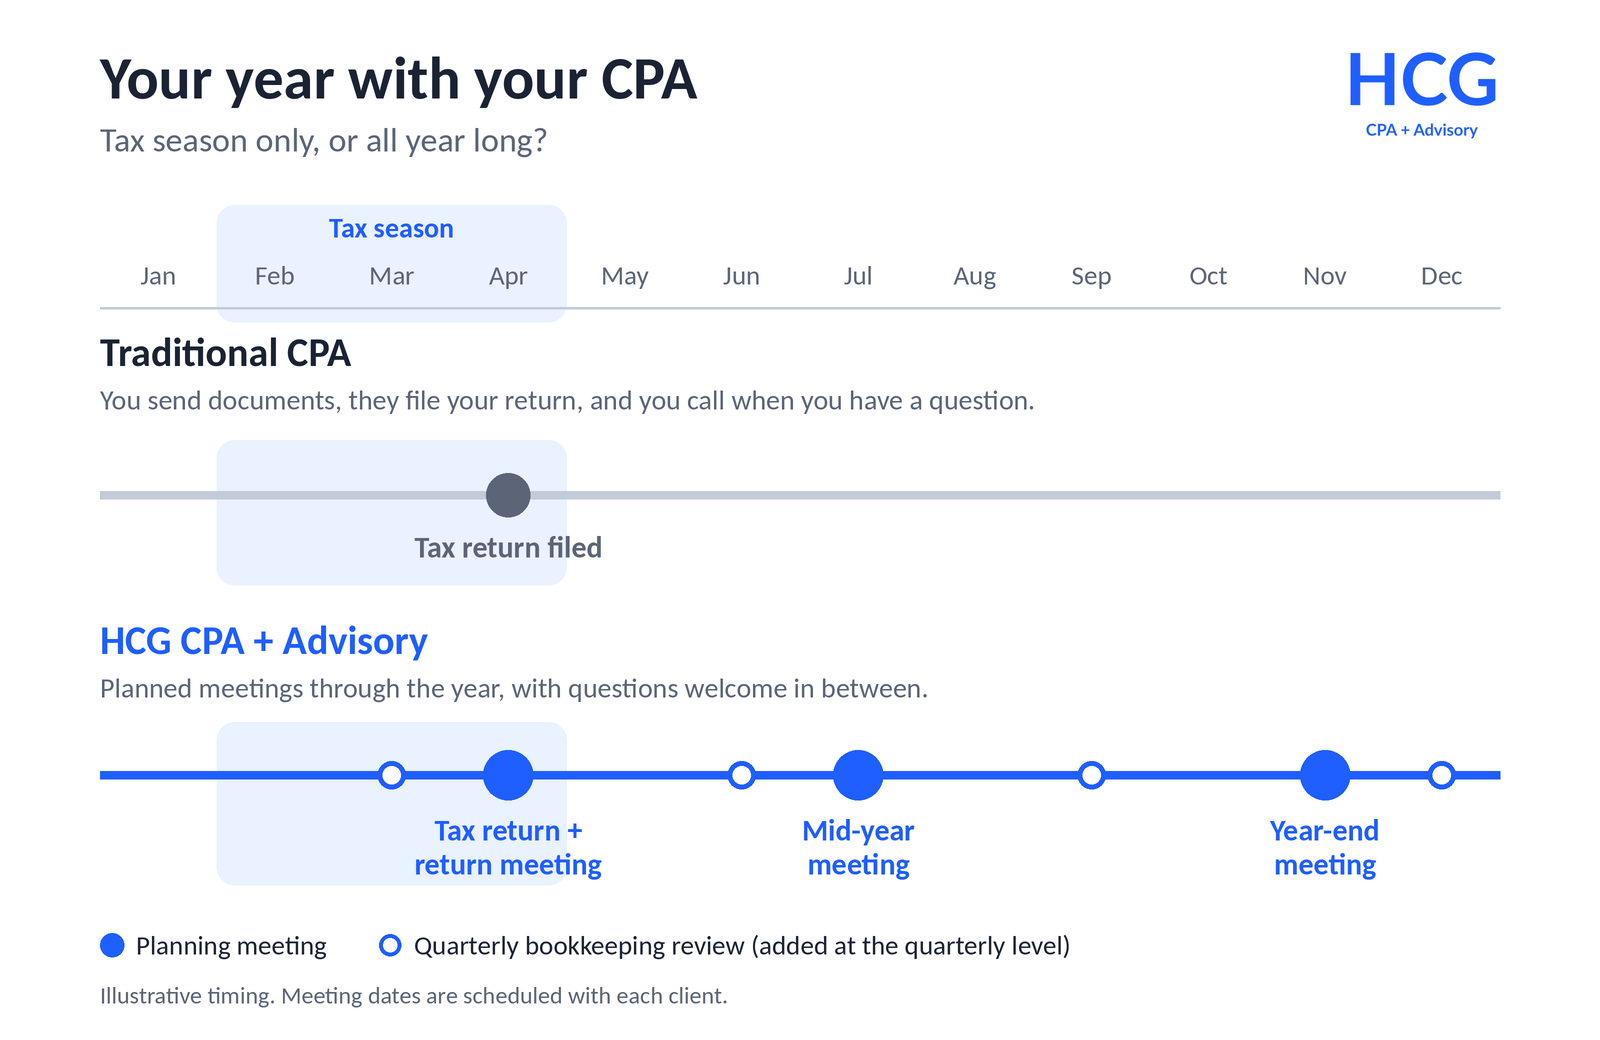
Does your CPA only call at tax time? Seven questions that show what advisory accounting is and what you may be missing. Fort Wayne CPA advisory.
Practical guidance for business owners on tax planning, business structure, cash flow, retirement strategies, and proactive financial decisions.
From a closet office to an advisory-focused CPA firm, see how our firm is evolving to help Indiana business owners plan ahead and make better decisions
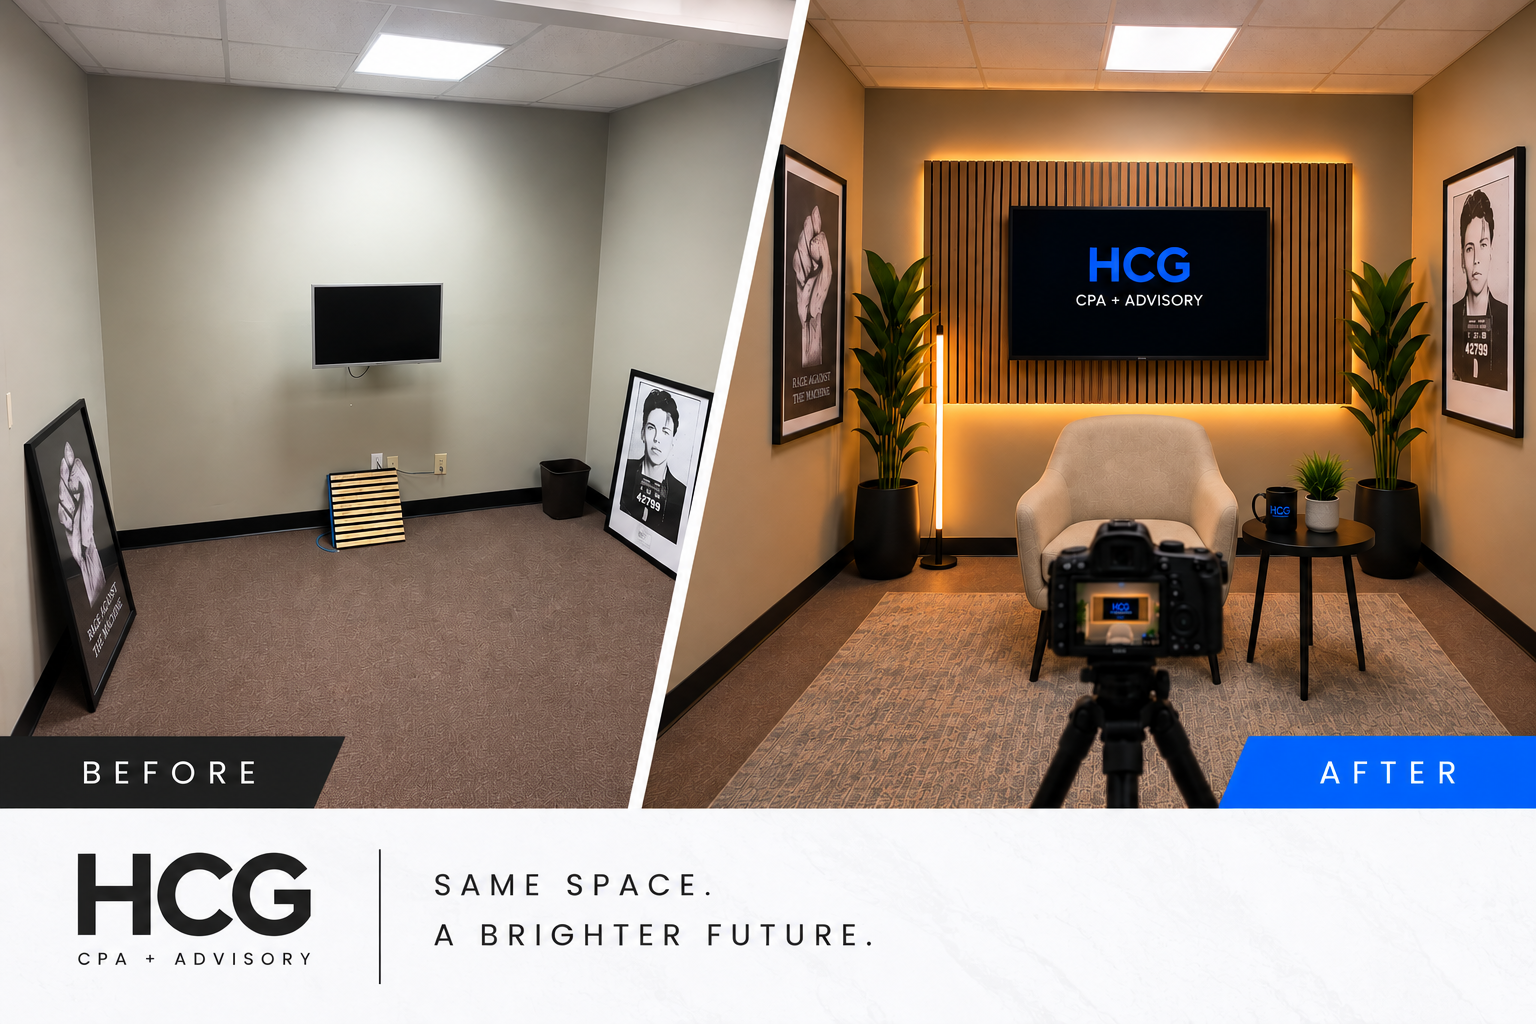
Why is a CPA firm building a studio? See how HCG CPA + Advisory is creating a better way to share timely, useful information with business owners year-round.
HCG CPA + Advisory is evolving. Learn why we’re updating our brand and office now—and how the changes reflect a more proactive approach for business owners.
From one client and no employees to a growing team, we share what building a CPA firm taught us about leadership, growth, and letting go.
Being a family-owned CPA firm shapes how HCG CPA + Advisory approaches independence, accountability, long-term thinking, and serving business owners.
In my last post, I talked about starting this firm from the back of a closet with one client, a makeshift desk, and an old power strip. But I didn’t start a CPA firm because I had always dreamed of owning a CPA firm. I started it because the traditional model didn’t make sense to me — especially after starting a small side business of my own and seeing things from the business owner’s side. Clients would send information into a black hole and wonder when they would hear back. Business owners would meet with their accountant after the year was already over, when most of the opportunities to actually change the outcome were gone. Large firms often reserved their best advice and attention for their largest clients, even though smaller business owners arguably needed that guidance more. Tax returns became the service instead of what I believed they should be: the end result of conversations happening throughout the year. And too often, the accountant knew the numbers but didn’t really know the business. None of that made sense to me. I thought a CPA firm could be more than the place you send documents once a year. I thought we could help business owners make better decisions before those decisions showed up on a tax return. That idea became the foundation of the firm. Pricing was another problem. At the first firm I worked for, we had “dynamic” pricing. In practice, that could mean charging a client more after a good year to supposedly make up for years when their bill had been discounted. Other clients might go an incredibly long time without receiving a bill, only to suddenly get hit with a huge invoice. As someone trying to run a business myself, I couldn’t understand that. How could a business owner budget for a professional relationship without knowing what it was going to cost? The traditional model was built around billing for time, yet employees were constantly being told to work faster. That created the wrong incentives. The focus became completing the deliverable efficiently instead of asking what else the client needed to know. Payroll could become an afterthought. Bookkeeping could become work used to fill the slower months. Questions about a client’s history could be viewed as time taking away from the task at hand. The system rewarded completing work. I wanted a system that rewarded helping the client. So when I started the firm in 2017, the concept was pretty simple. Find out what the client actually needs. Agree on the scope. Give them a predictable monthly price. Review that relationship every 9–12 months and adjust when their needs change. And most importantly, don’t disappear between tax returns. From the beginning, I wanted the relationship to include tax return preparation, mid-year tax planning, year-end planning, and responsive communication throughout the year. At the time, proactive planning and upfront pricing were far less common in the small-business CPA market. A business owner getting a call that said, “Let’s meet in July and see how the first half of the year went,” was not the experience many owners expected from their accountant. But it made perfect sense to me. If we waited until tax season to have that conversation, we weren’t planning anymore. We were reporting history. The response was great — once I could get business owners to give a new firm a chance. Over time, that simple concept grew into something much bigger. People smarter than me helped develop it into what the profession now broadly calls advisory, with a much wider scope and greater ambition than what I originally envisioned. But the underlying idea hasn’t changed. Business owners deserve to know what they’re paying. They deserve honest advice, even when the answer isn’t what they expected. They deserve regular conversations about what is happening in their business and what is coming next. And they deserve a CPA who understands that the goal isn’t simply to produce an accurate tax return. The goal is to help them make better decisions before we get there. That’s why I started the firm. Transparent pricing. Honest advice. Regular conversations. Built for Business Owners. CPA Led. Strategy Focused.
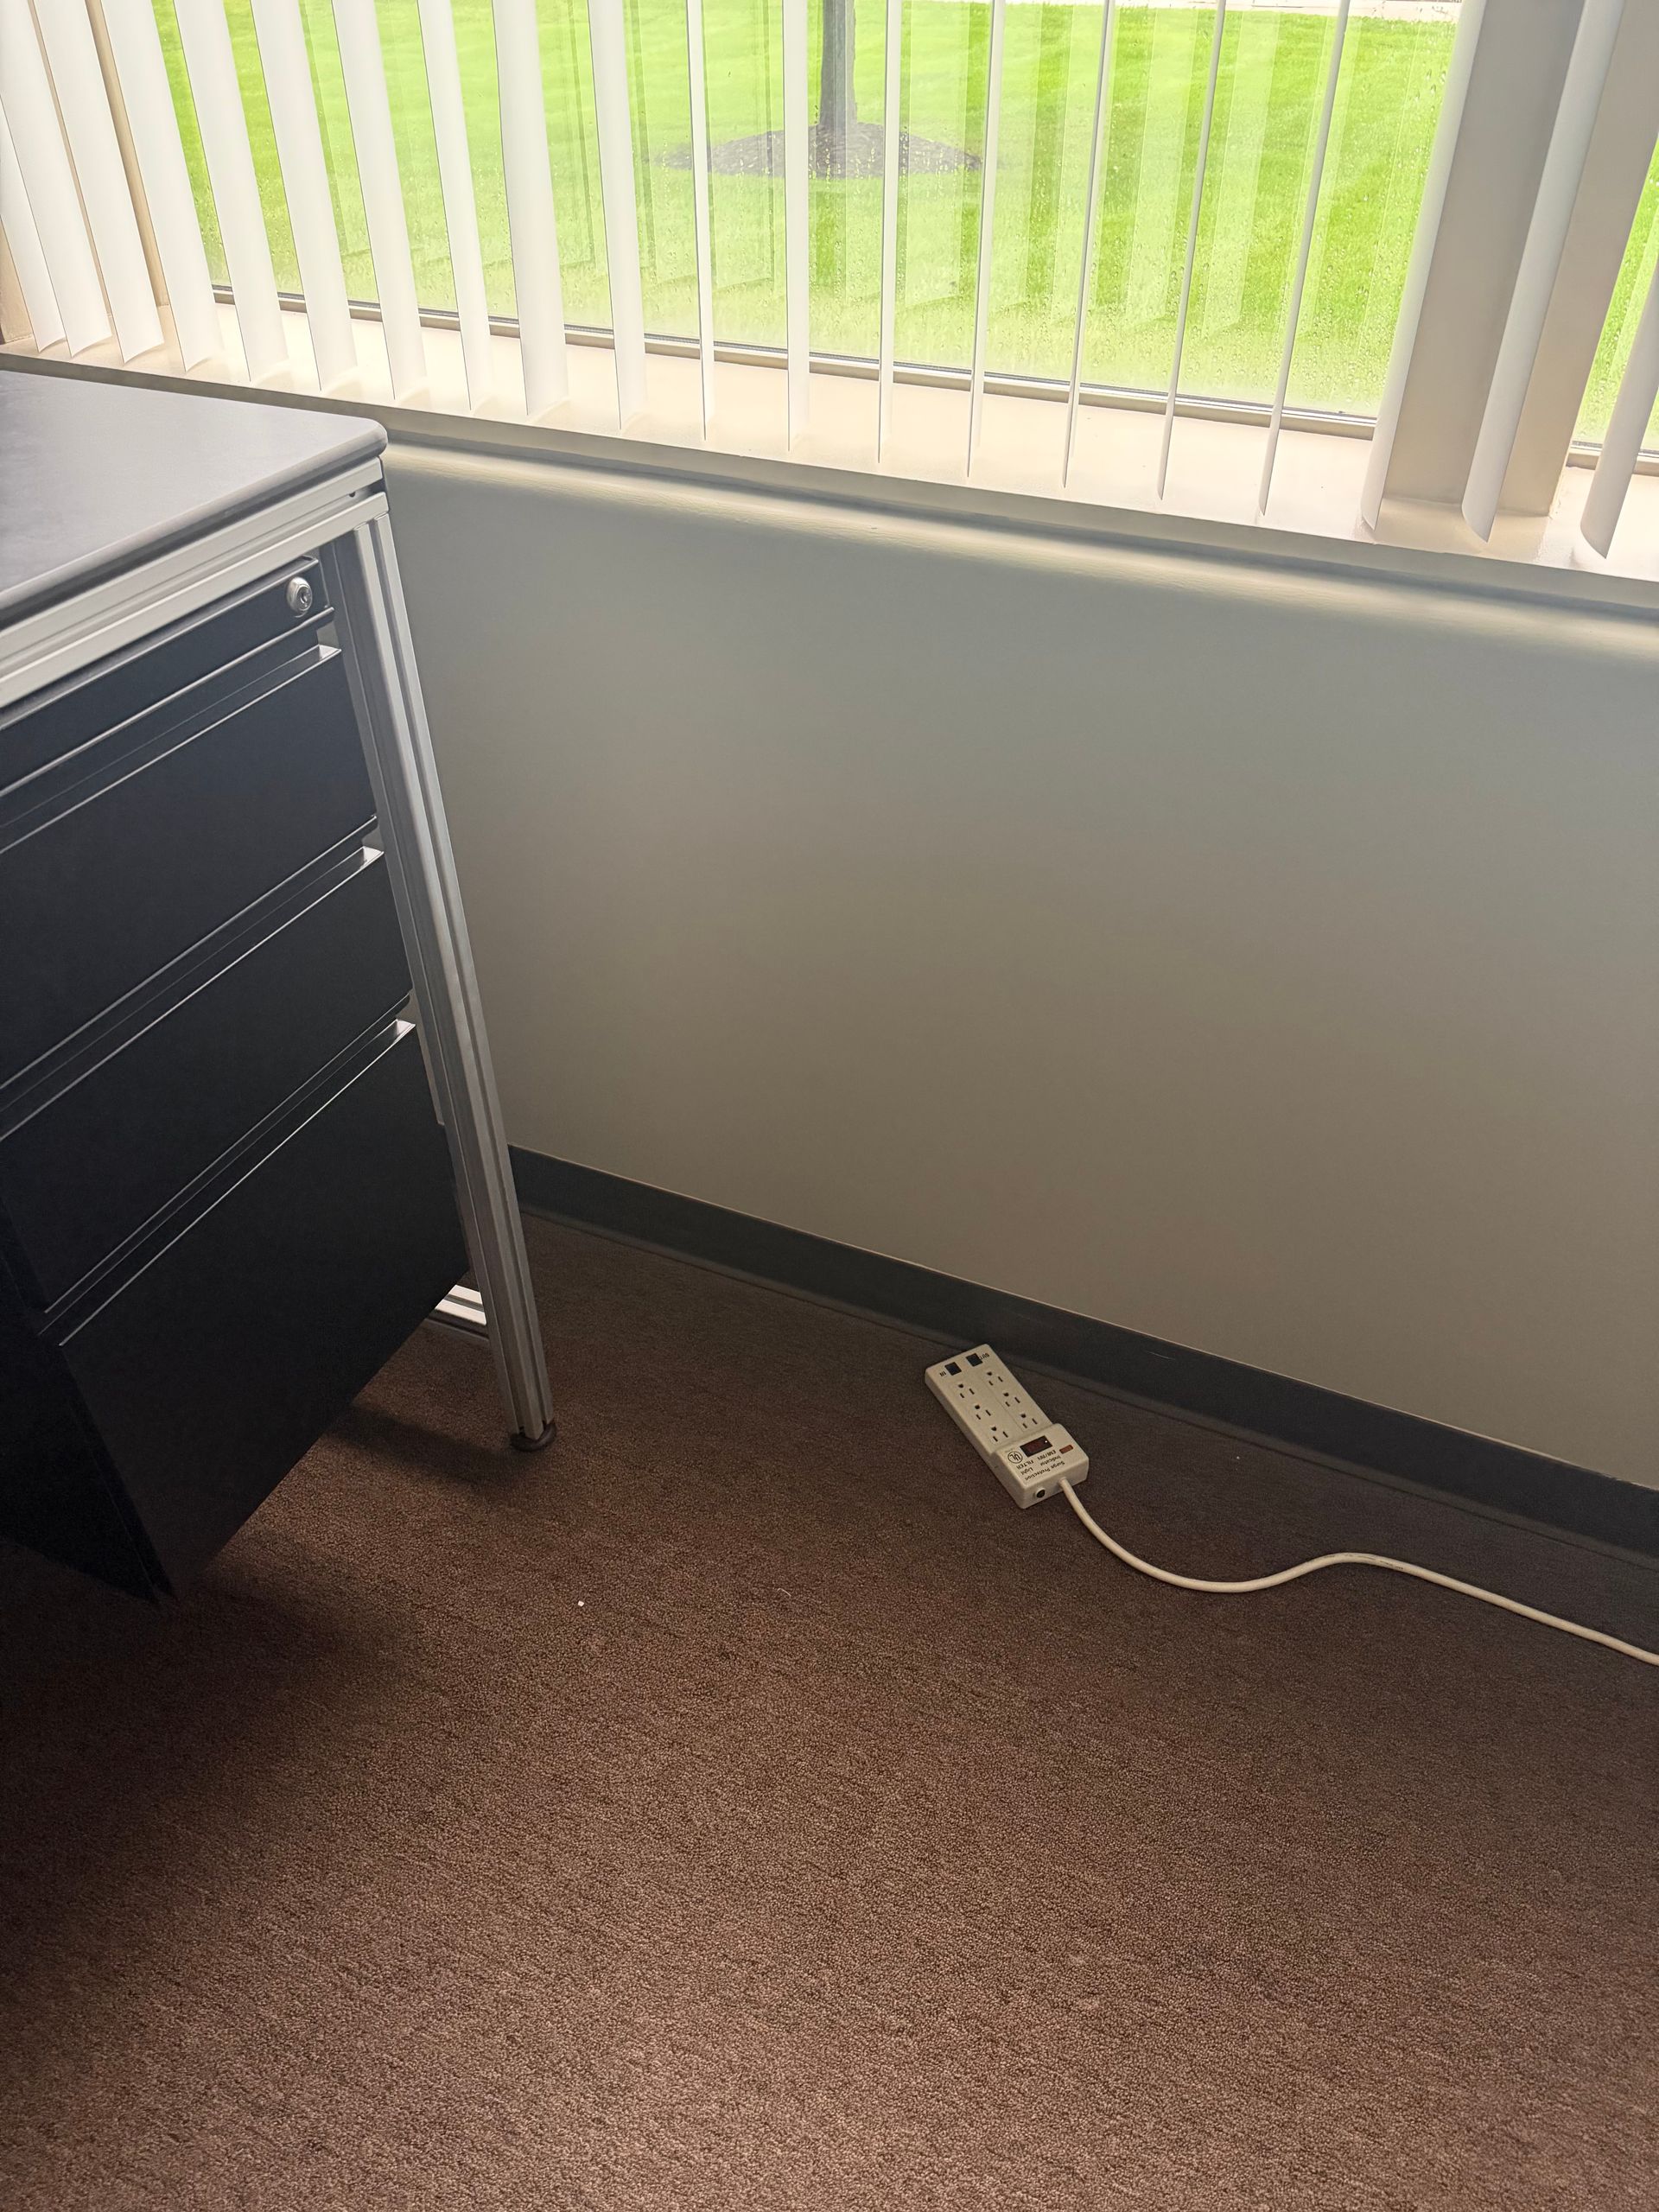
An old power strip from my beginning became an unexpected reminder of how easy it is for business owners to overlook how far they’ve come.
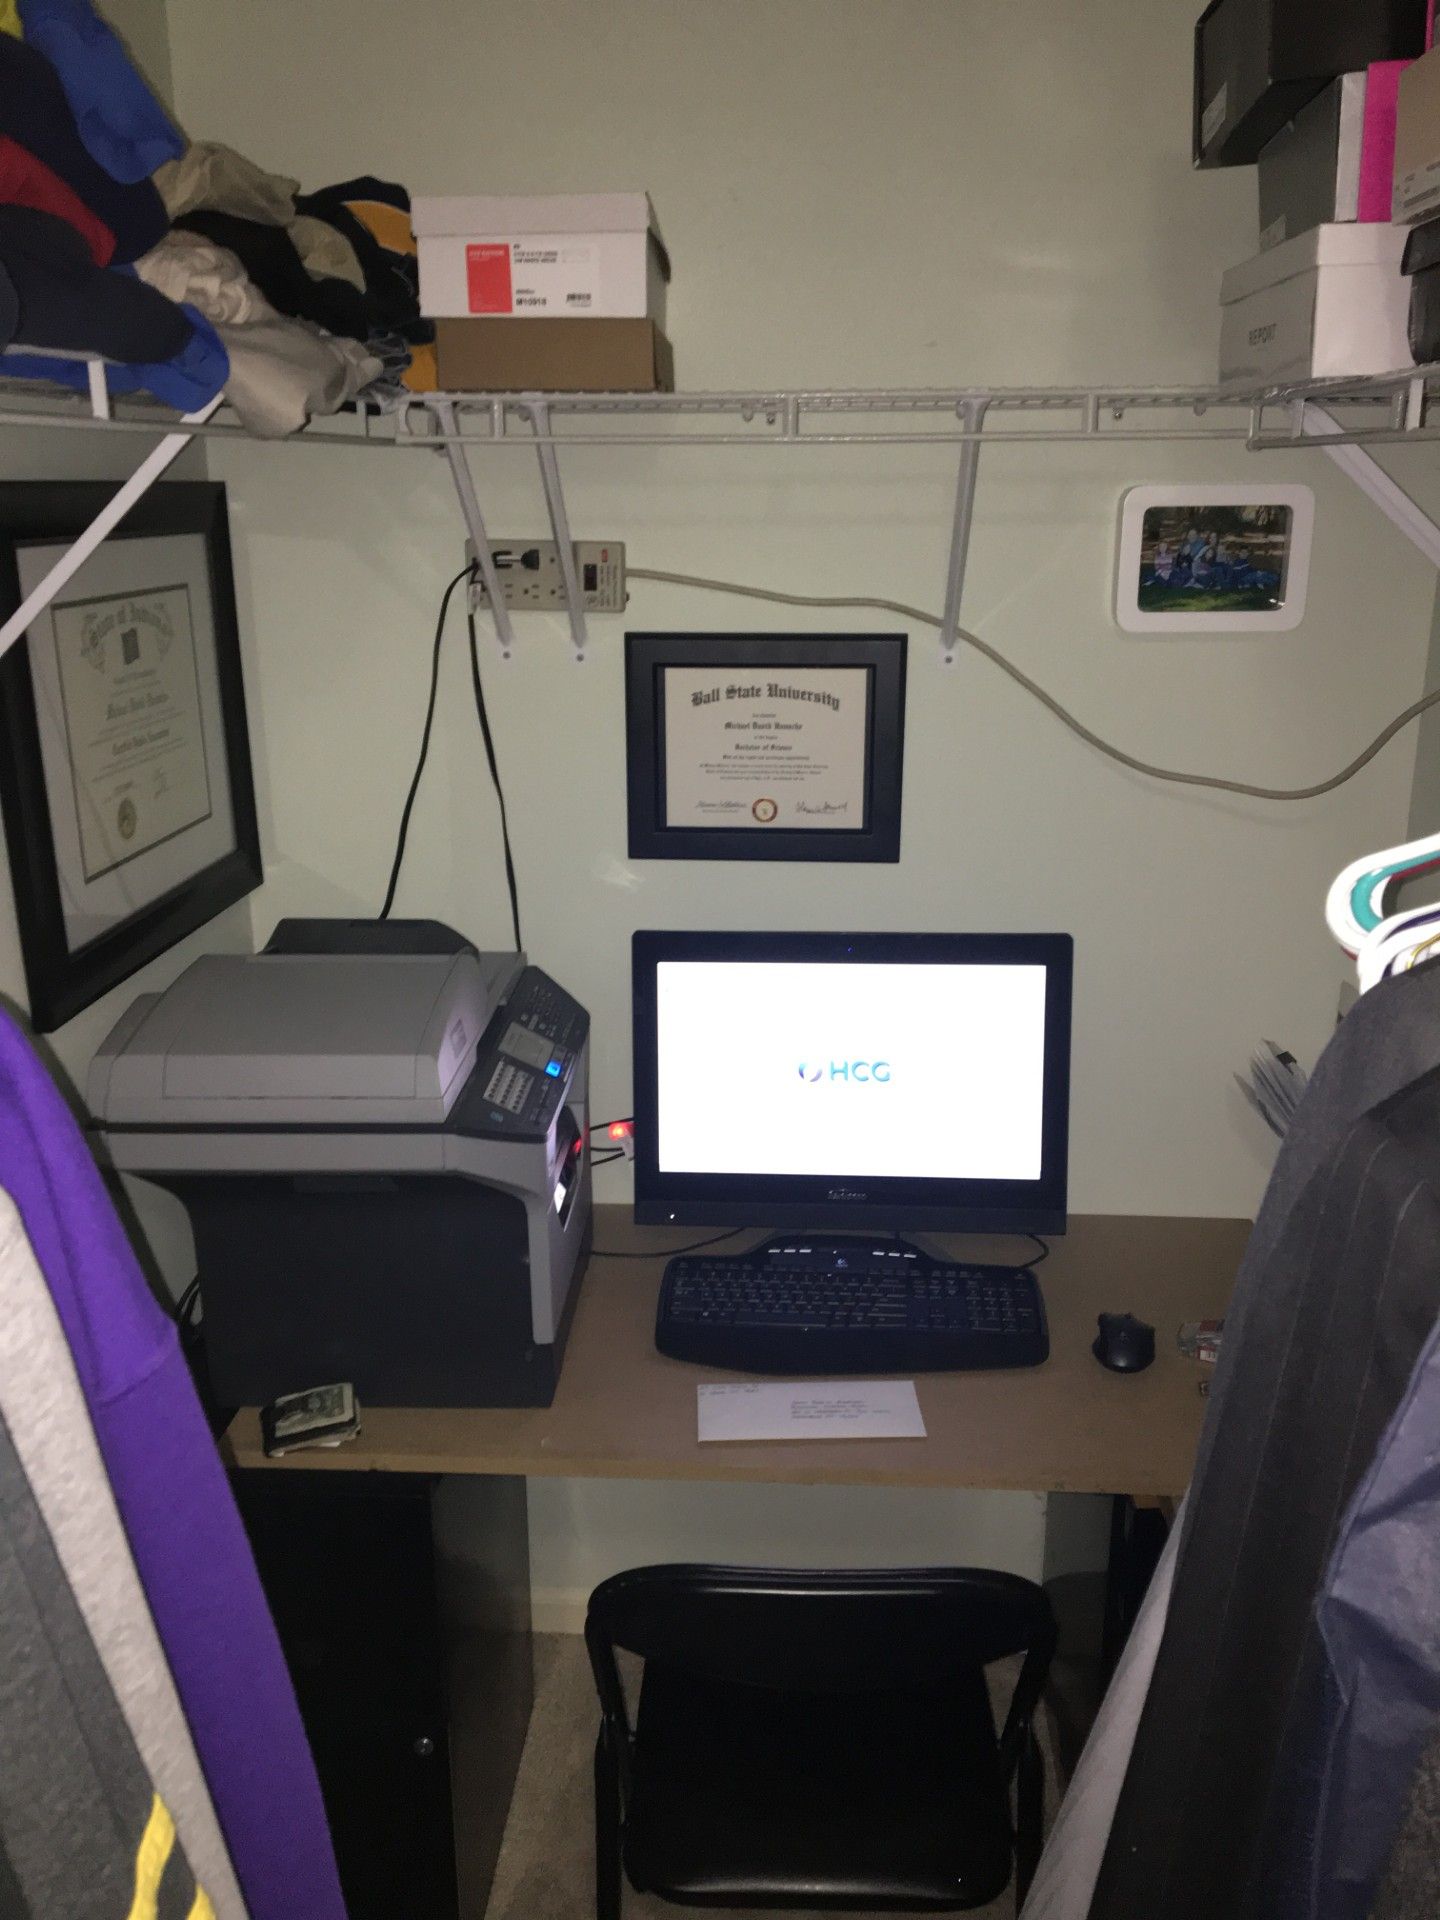
Our family-owned CPA firm started with almost no clients, no employees, and a closet for an office. Here’s why we started—and what hasn’t changed.

Tax nexus can create state tax filing obligations long before business owners realize it. Learn how nexus works, why it matters, and the common mistakes that lead to unexpected tax bills.
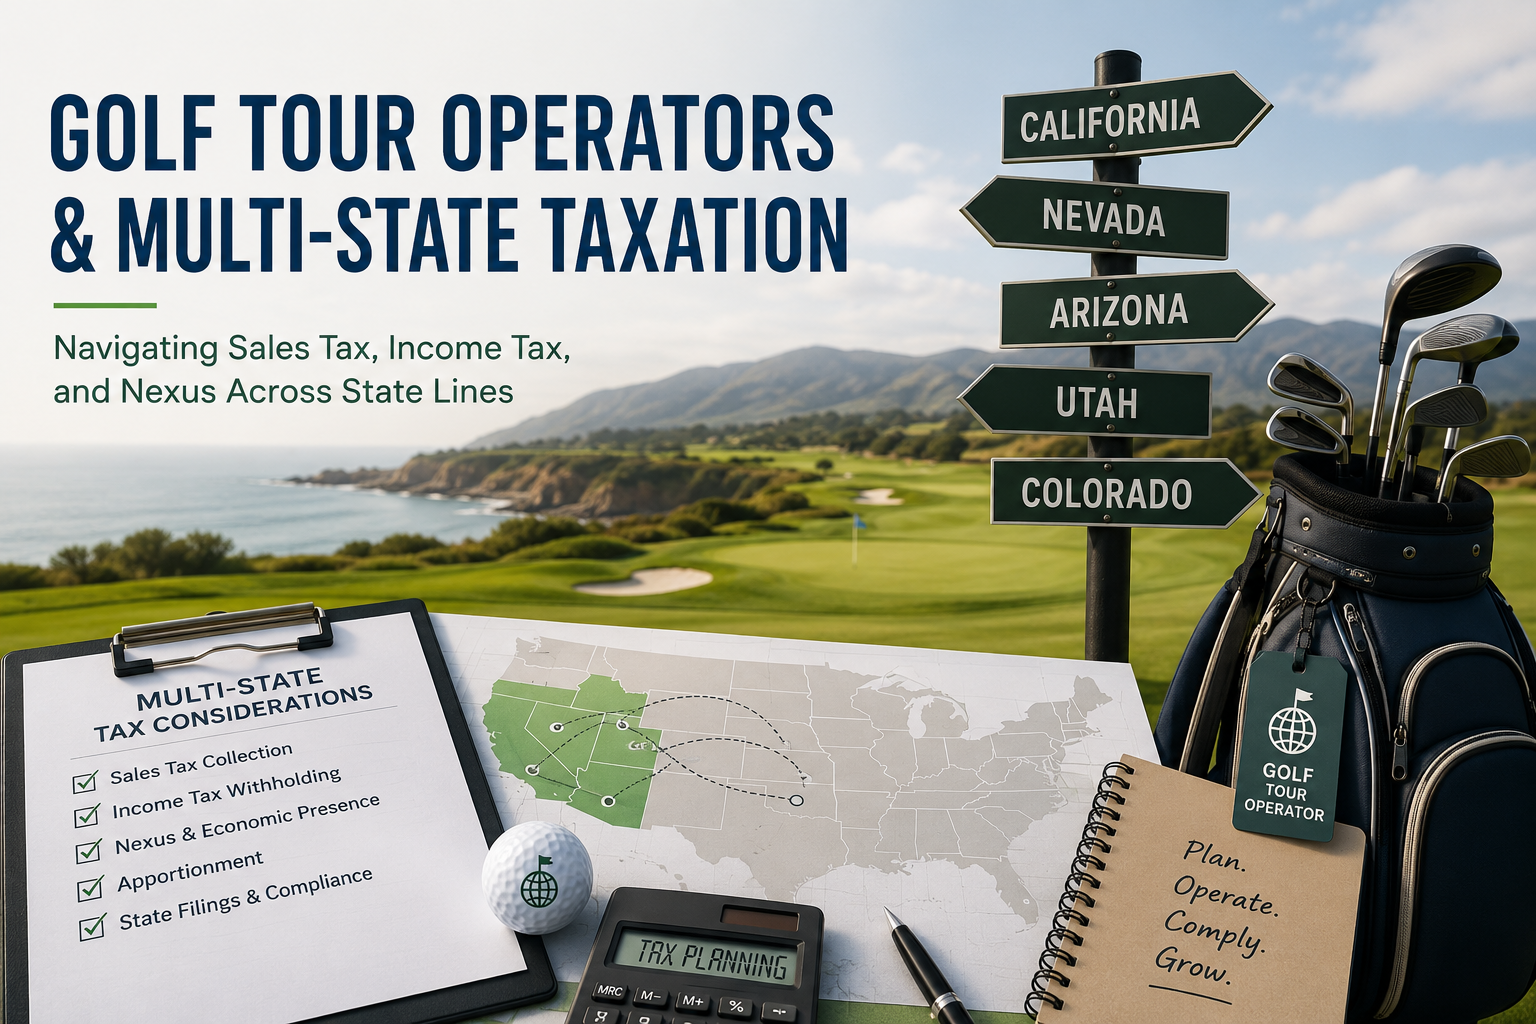
Golf tour operators often create tax obligations in multiple states without realizing it. Learn the key multi-state filing risks, nexus rules, and tax planning strategies every tour operator should know.
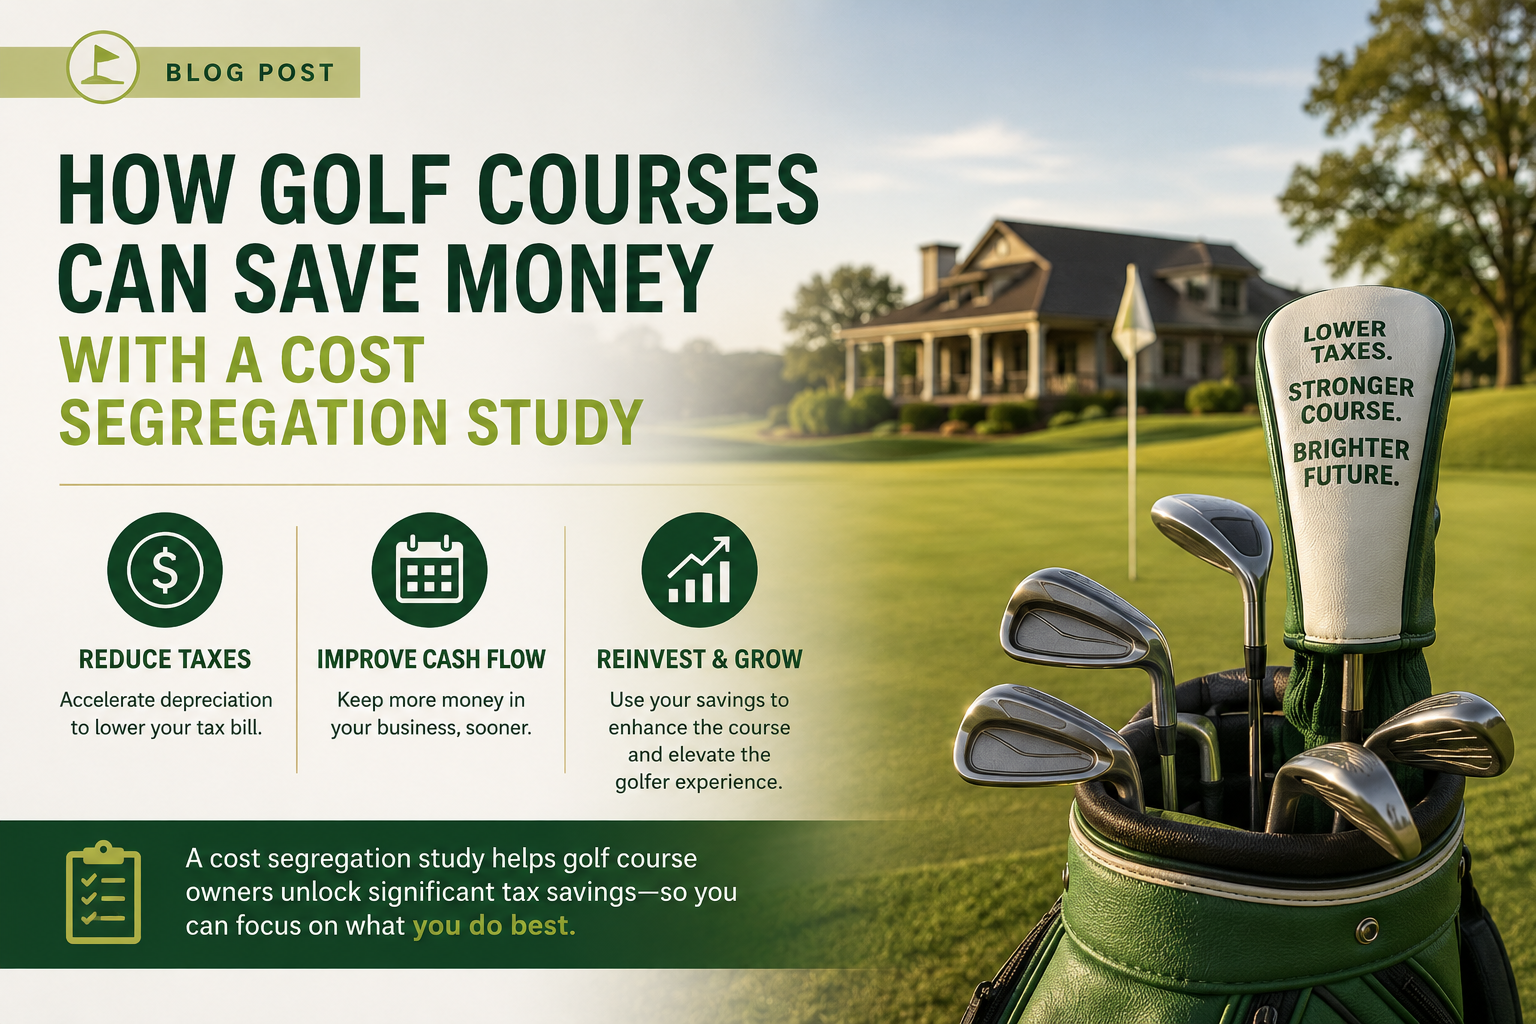
Golf course owners may be sitting on significant missed tax deductions. Learn how a cost segregation study can help recover prior-year depreciation and improve cash flow without amending past returns.
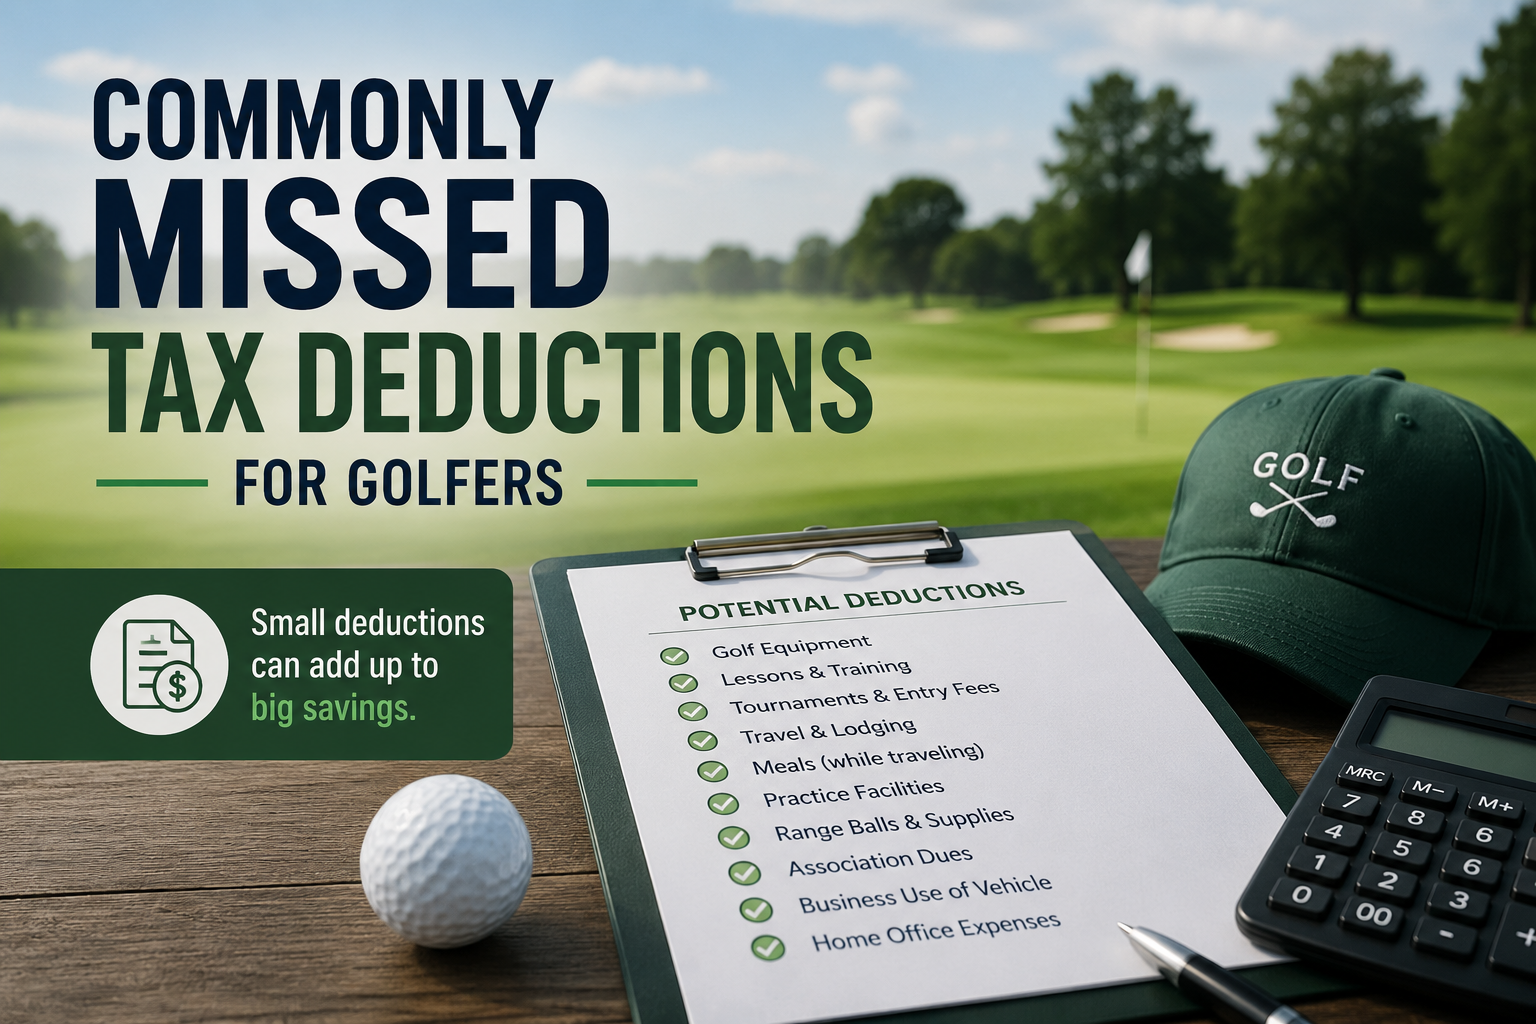
Many golf courses leave valuable tax deductions on the table every year. Learn the most commonly missed tax-saving opportunities and proactive planning strategies for golf course owners.
Golf courses rely on a network of vendors, tour operators, pro shops, and service providers. Learn why tracking margins is critical for profitability and long-term growth.
Discover how golf courses can use data analytics, technology, and modern management tools to improve profitability, increase member engagement, and make better business decisions.
Learn what restaurant prime cost is, how to calculate it, ideal target ranges, and why monitoring it is critical to restaurant profitability and long-term success.
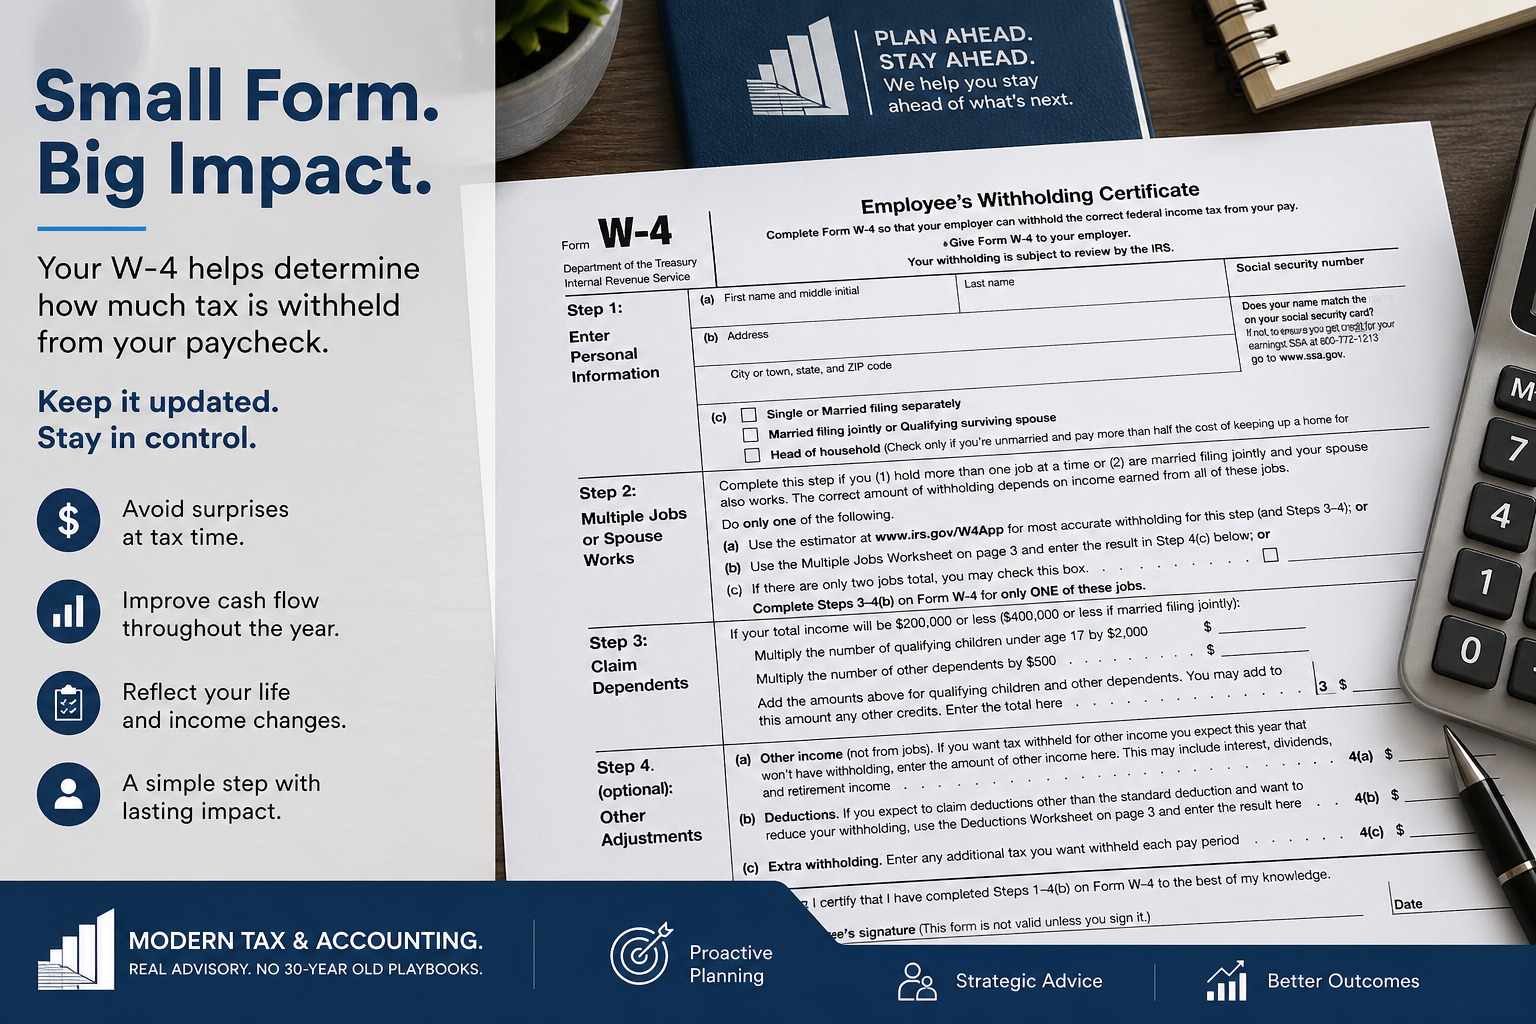
Not sure if your paycheck withholding is right? Learn why updating your W-4 matters, when to do it, and how to fill it out correctly to avoid surprises at tax time.
Accurate bookkeeping isn’t just about clean records — it drives better tax strategy, cash flow, and decisions. Learn why your CPA should be part of the process.
Your tax return shows what happened last year — not what to do next. Learn what’s missing and how proactive tax planning helps business owners reduce taxes and build wealth.
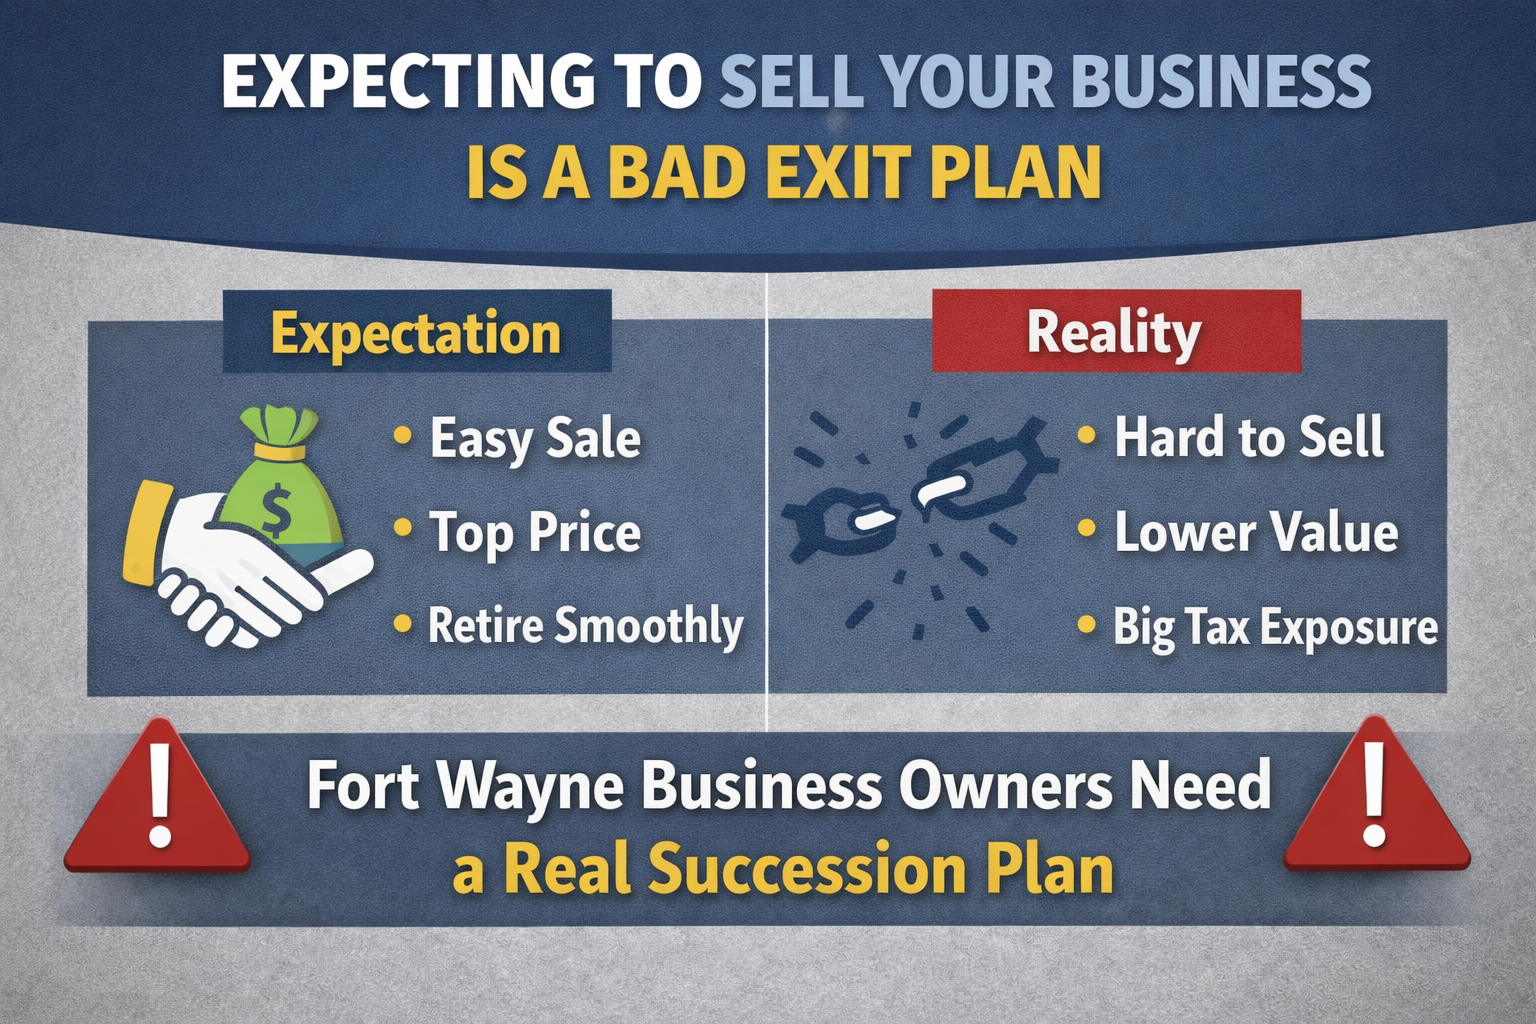
Planning to sell your business someday? That’s not a strategy. Fort Wayne business owners need a real succession plan to protect value and reduce taxes.
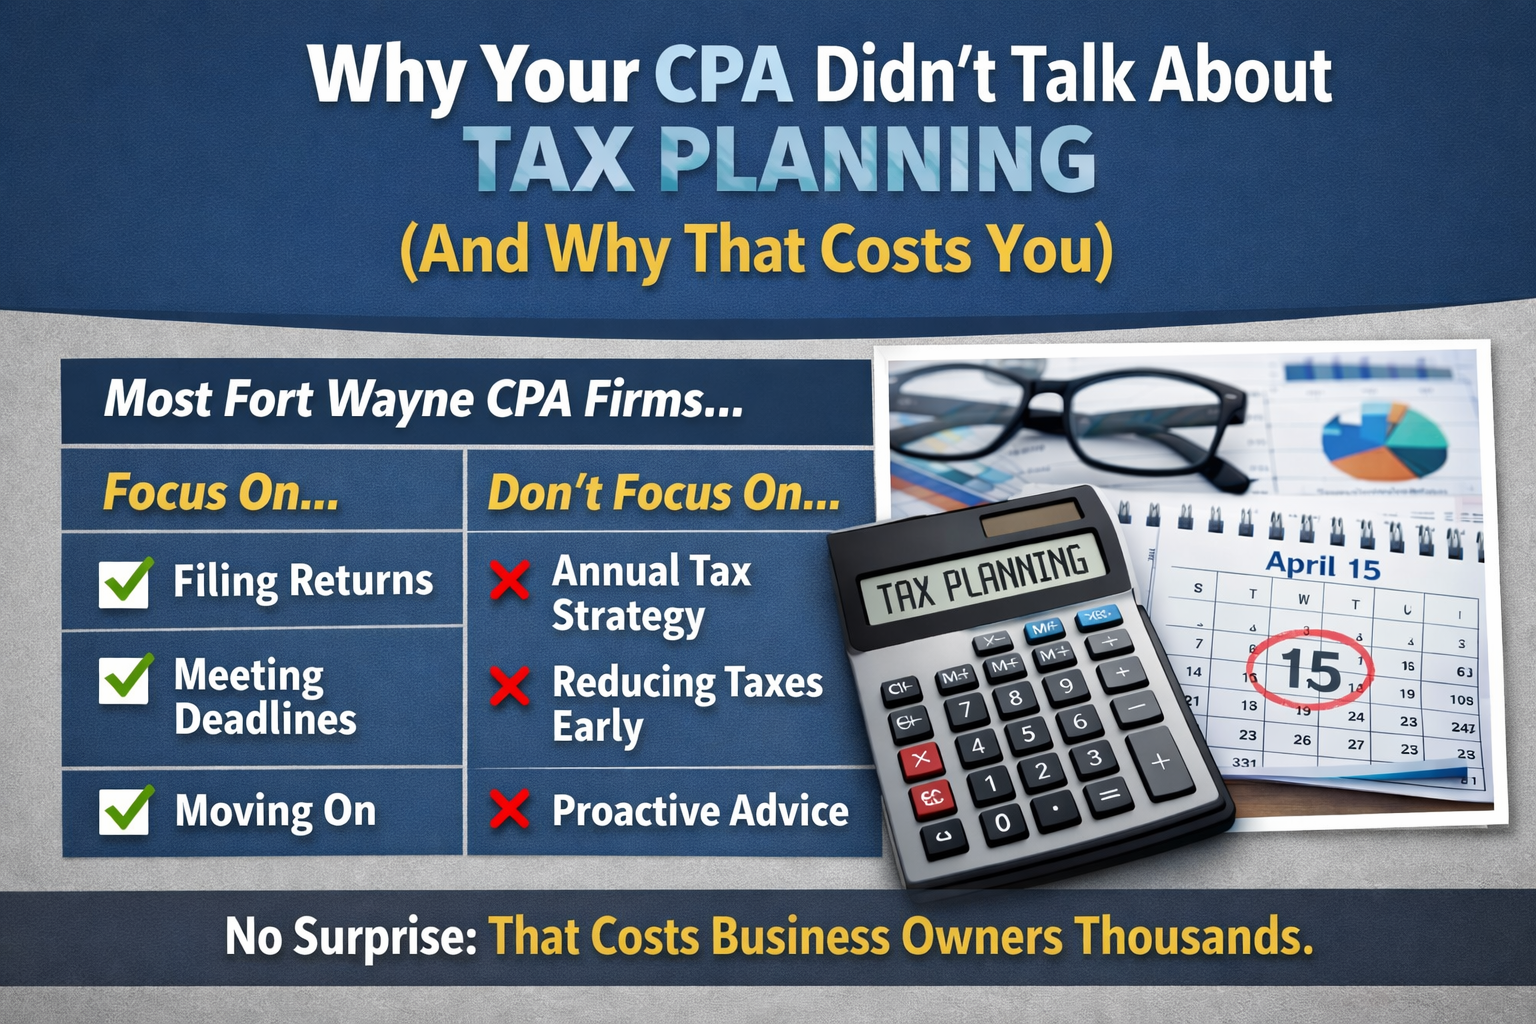
Most Fort Wayne CPAs don’t talk about tax planning—and it costs business owners thousands. Here’s why, and what to do instead.
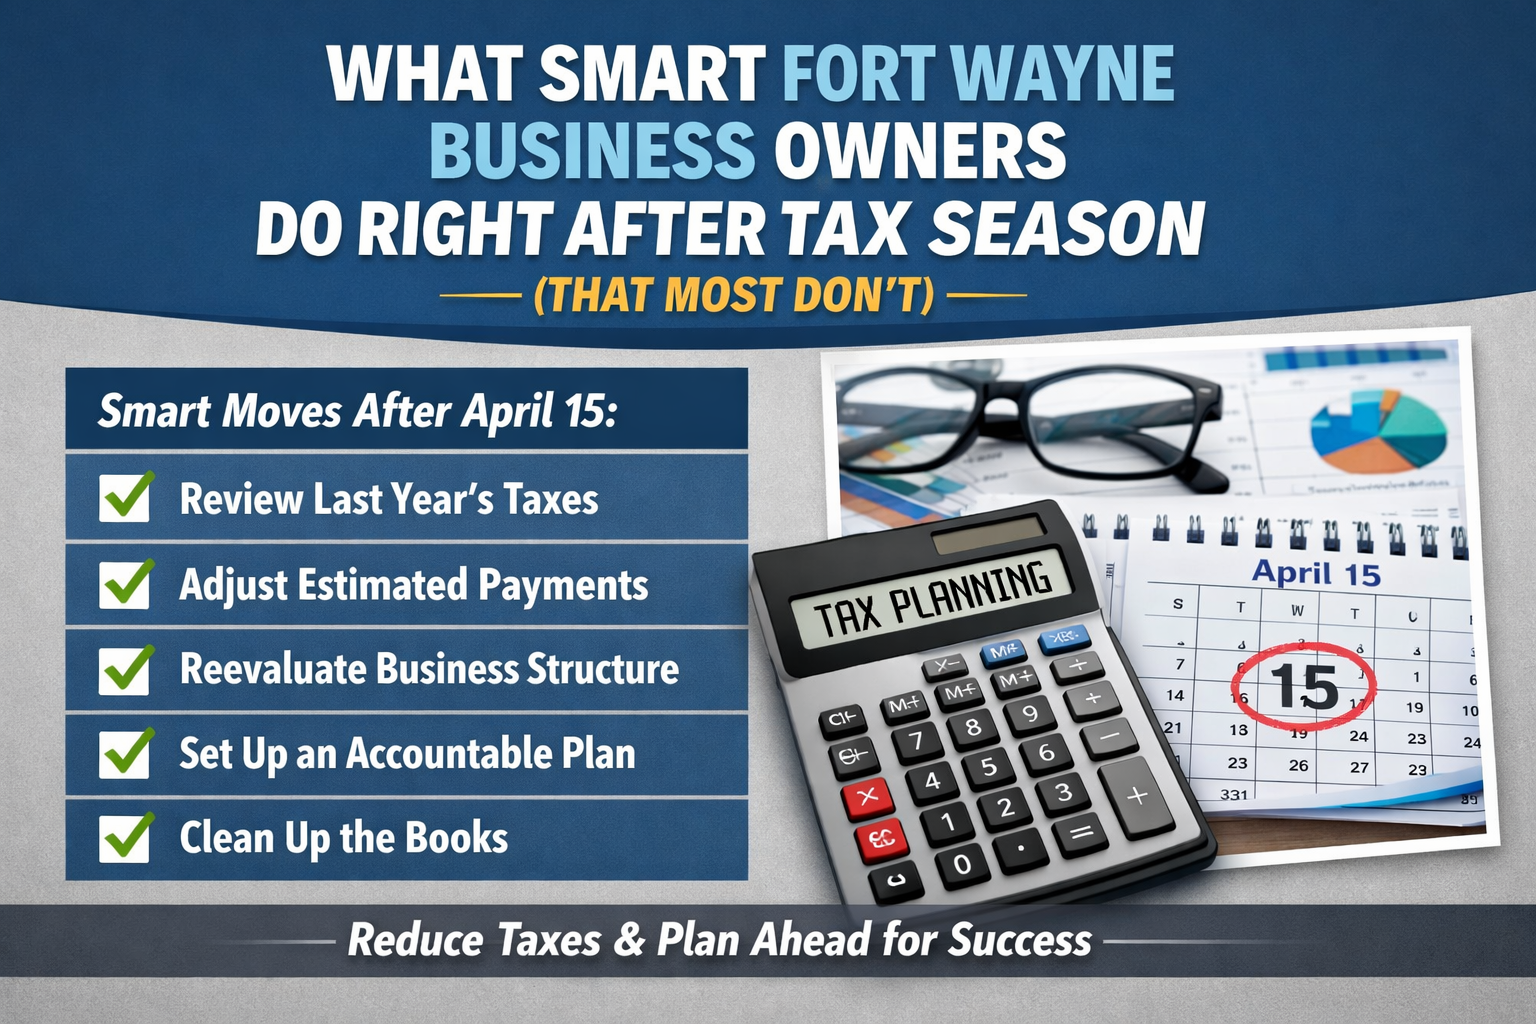
Tax season is over—but smart Fort Wayne business owners know the real work starts now. Here’s what to do after filing to reduce taxes and stay ahead.
Learn how Fort Wayne and Huntington business owners can combine cost segregation and S-Corp strategies to reduce taxes and improve cash flow.
Is cost segregation worth it for Huntington, Indiana rental property owners? Learn when it makes sense, potential tax savings, and key mistakes to avoid.
Learn how cost segregation in Fort Wayne can accelerate depreciation, reduce taxes, and improve cash flow for real estate owners and business investors.
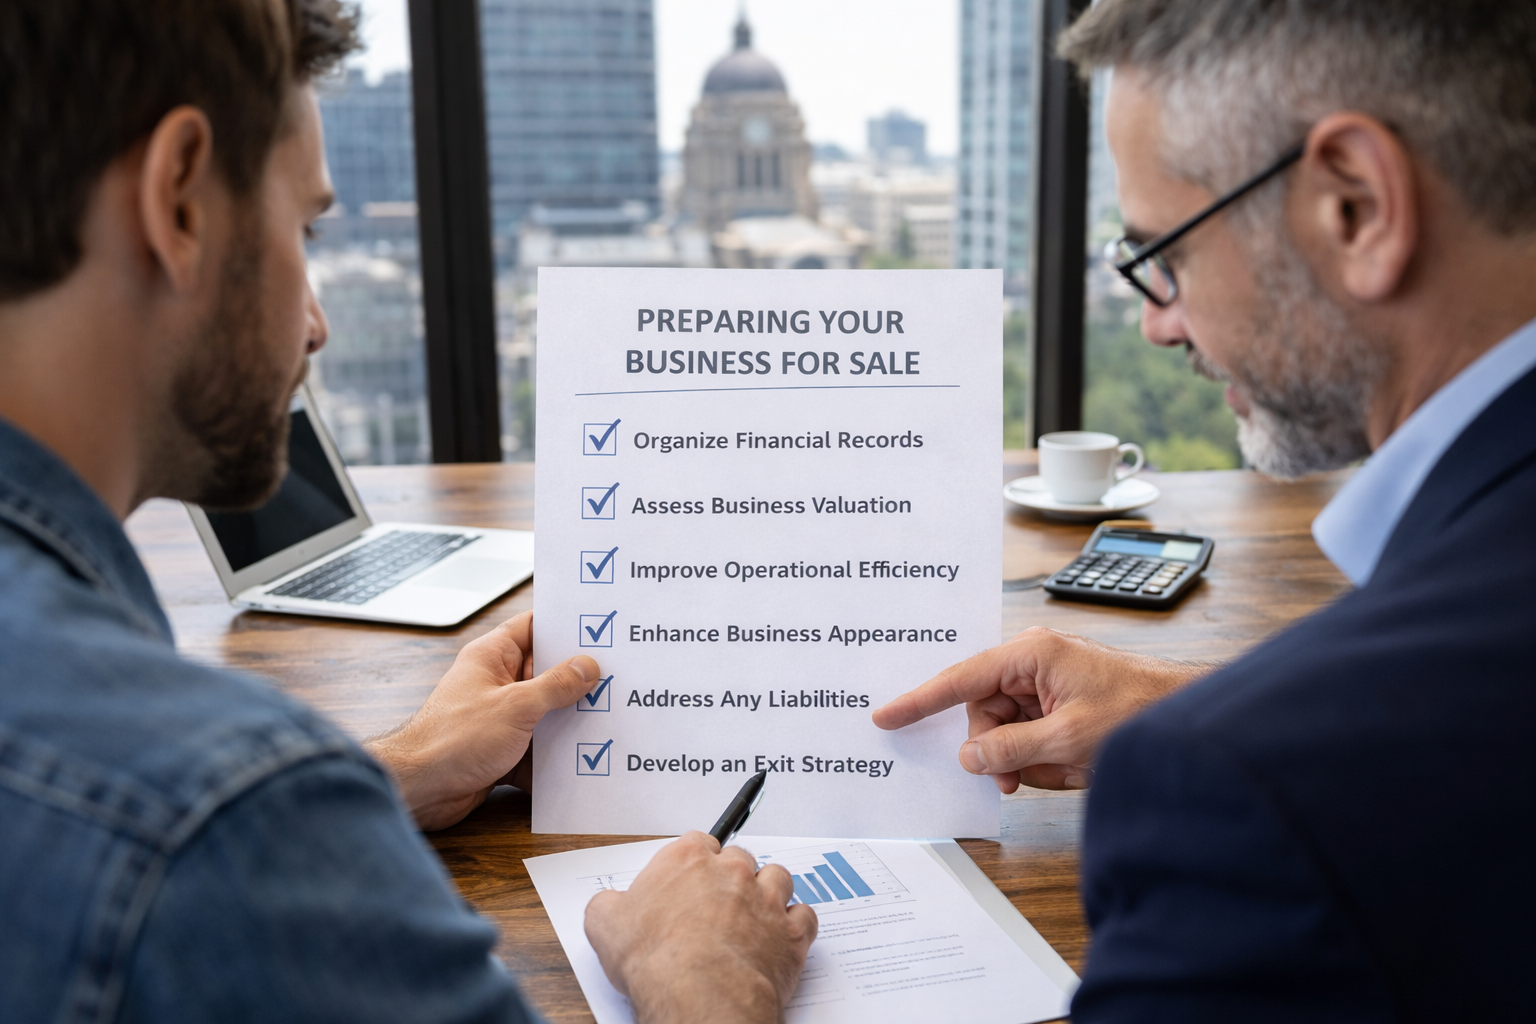
Exit planning for Indiana business owners should start years before selling. Learn how Fort Wayne CPAs help maximize value and minimize taxes.
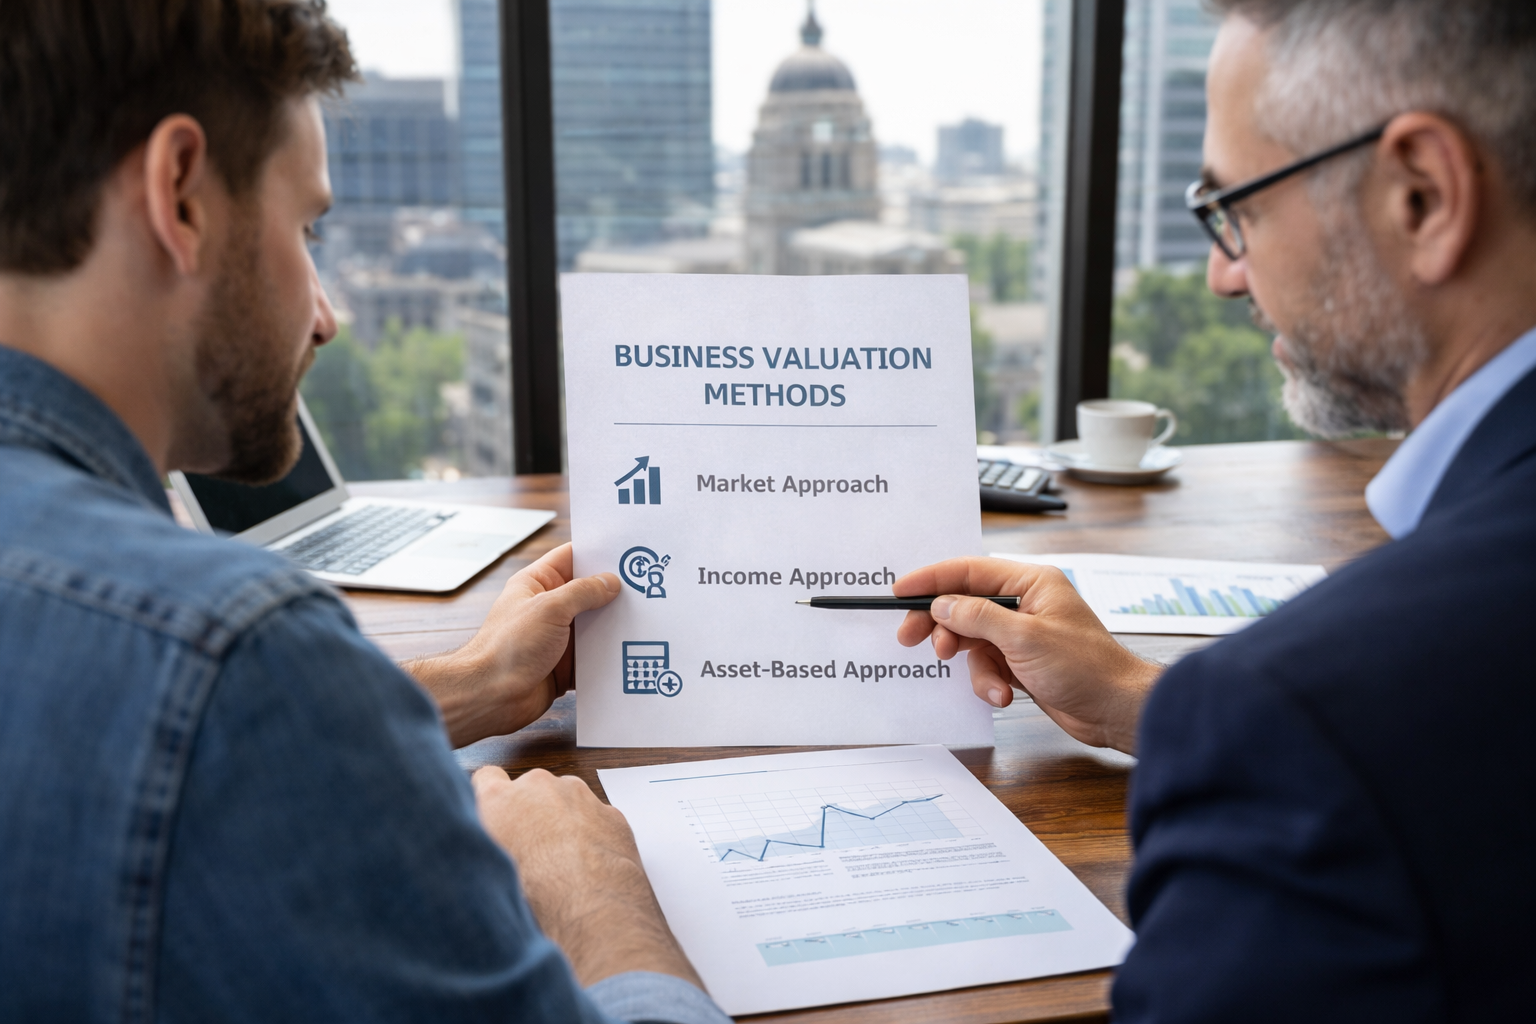
Wondering what your business is worth in Fort Wayne or Huntington? Learn valuation methods and how to increase your value before selling.
Planning on selling your business in Fort Wayne? Learn proactive tax strategies to reduce capital gains and keep more of your sale proceeds.
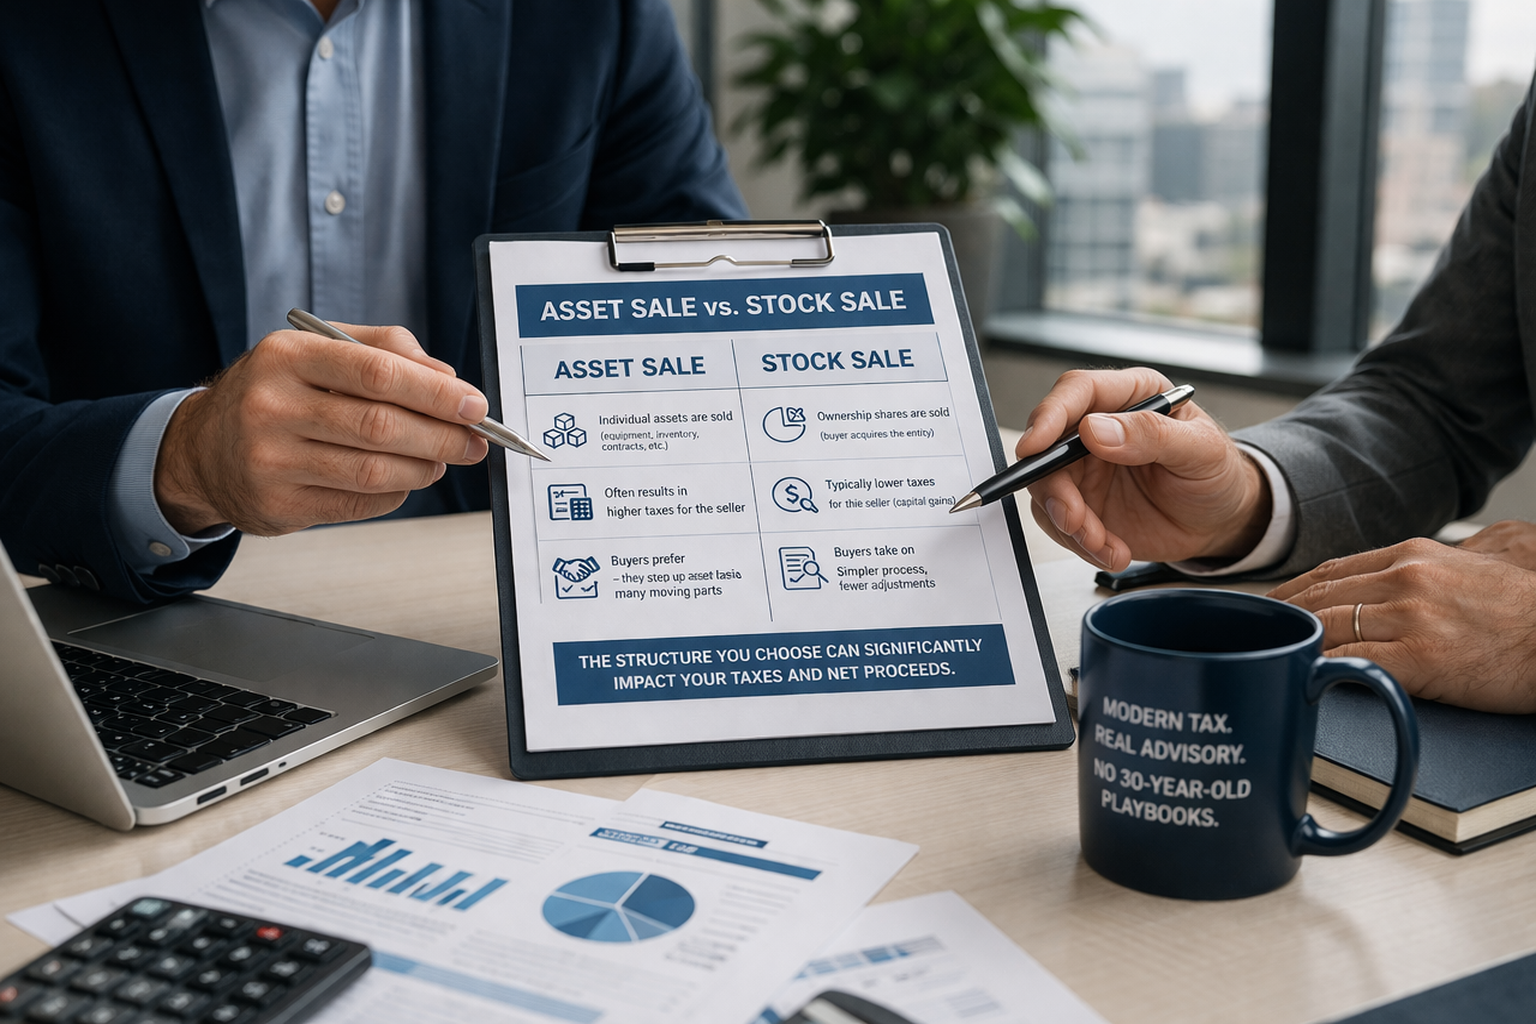
Asset vs stock sale in Indiana can drastically impact your taxes. Learn how Fort Wayne business owners should structure their deal before selling.
Confused about the difference between a Fractional CFO, CPA, and bookkeeper? Learn who does what—and how the right financial team can improve profitability, cash flow, and tax strategy.
Not sure if you need a Fractional CFO? Discover 7 key financial warning signs—from cash flow issues to surprise tax bills—that indicate it’s time to bring in strategic financial leadership
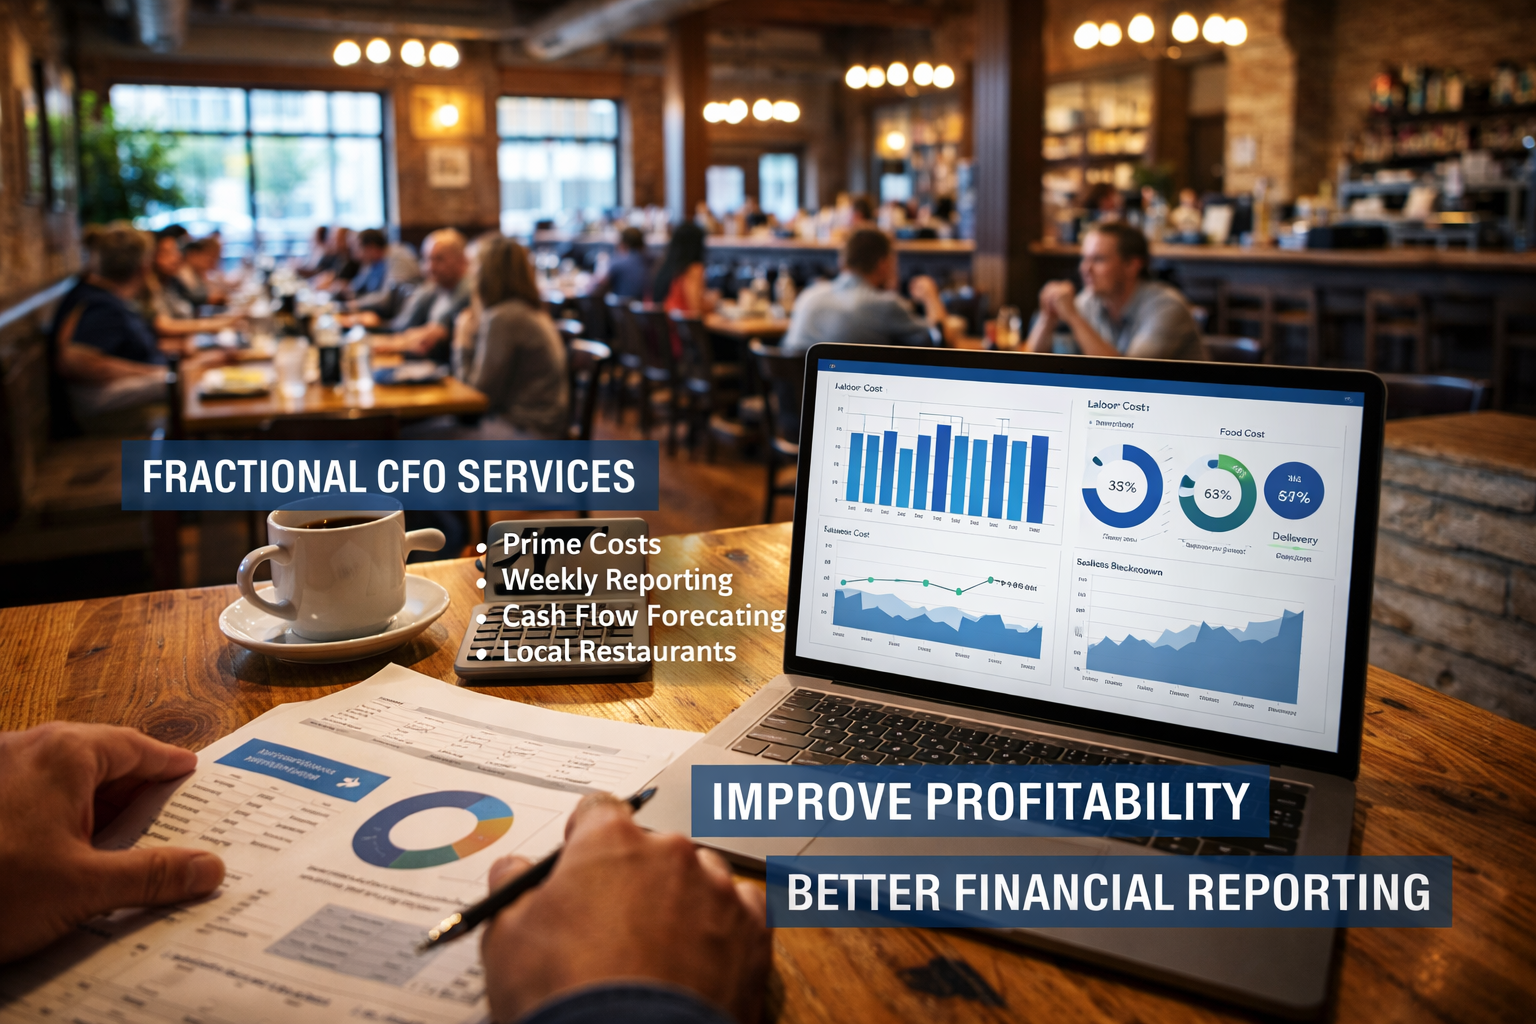
Struggling with restaurant profits? Discover how Huntington, IN restaurants use fractional CFO services and better financial reporting to boost margins and cash flow.
Discover the 5 hidden profit leaks a Fractional CFO can uncover in the first 90 days. Learn how to improve cash flow, increase margins, and reduce tax liability with strategic financial insights
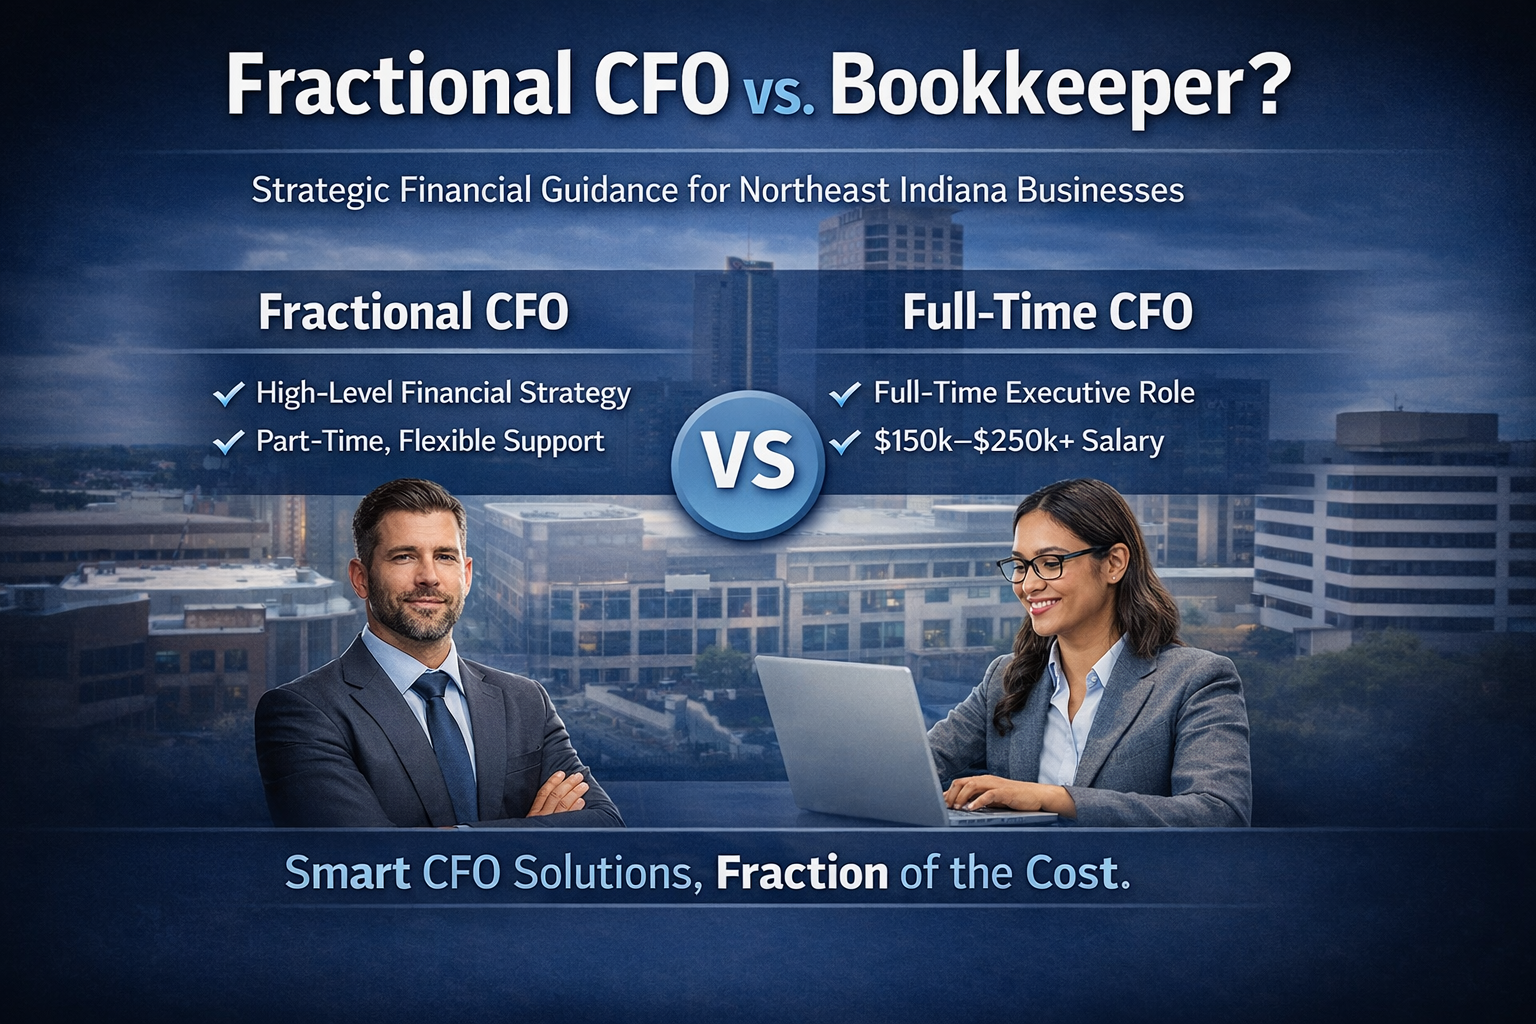
Fractional CFO vs bookkeeper explained for Northeast Indiana businesses. Compare services, costs, and when to hire a CFO in Fort Wayne
S-Corp vs LLC in Indiana: Learn when an S-Corp election can reduce taxes for small business owners and how to choose the right structure in 2026.
Fort Wayne business owners: learn the difference between CPAs and Enrolled Agents and why licensed tax professionals are essential for proactive tax planning.
Serious business owners trust licensed professionals. Learn why working with Fort Wayne CPAs or Enrolled Agents helps reduce tax risk and improve planning.
Looking for a proactive CPA in Fort Wayne? Learn what real tax planning and advisory should look like for Northeast Indiana businesses.